- About Us About Us
- How it Works How it Works
-
-
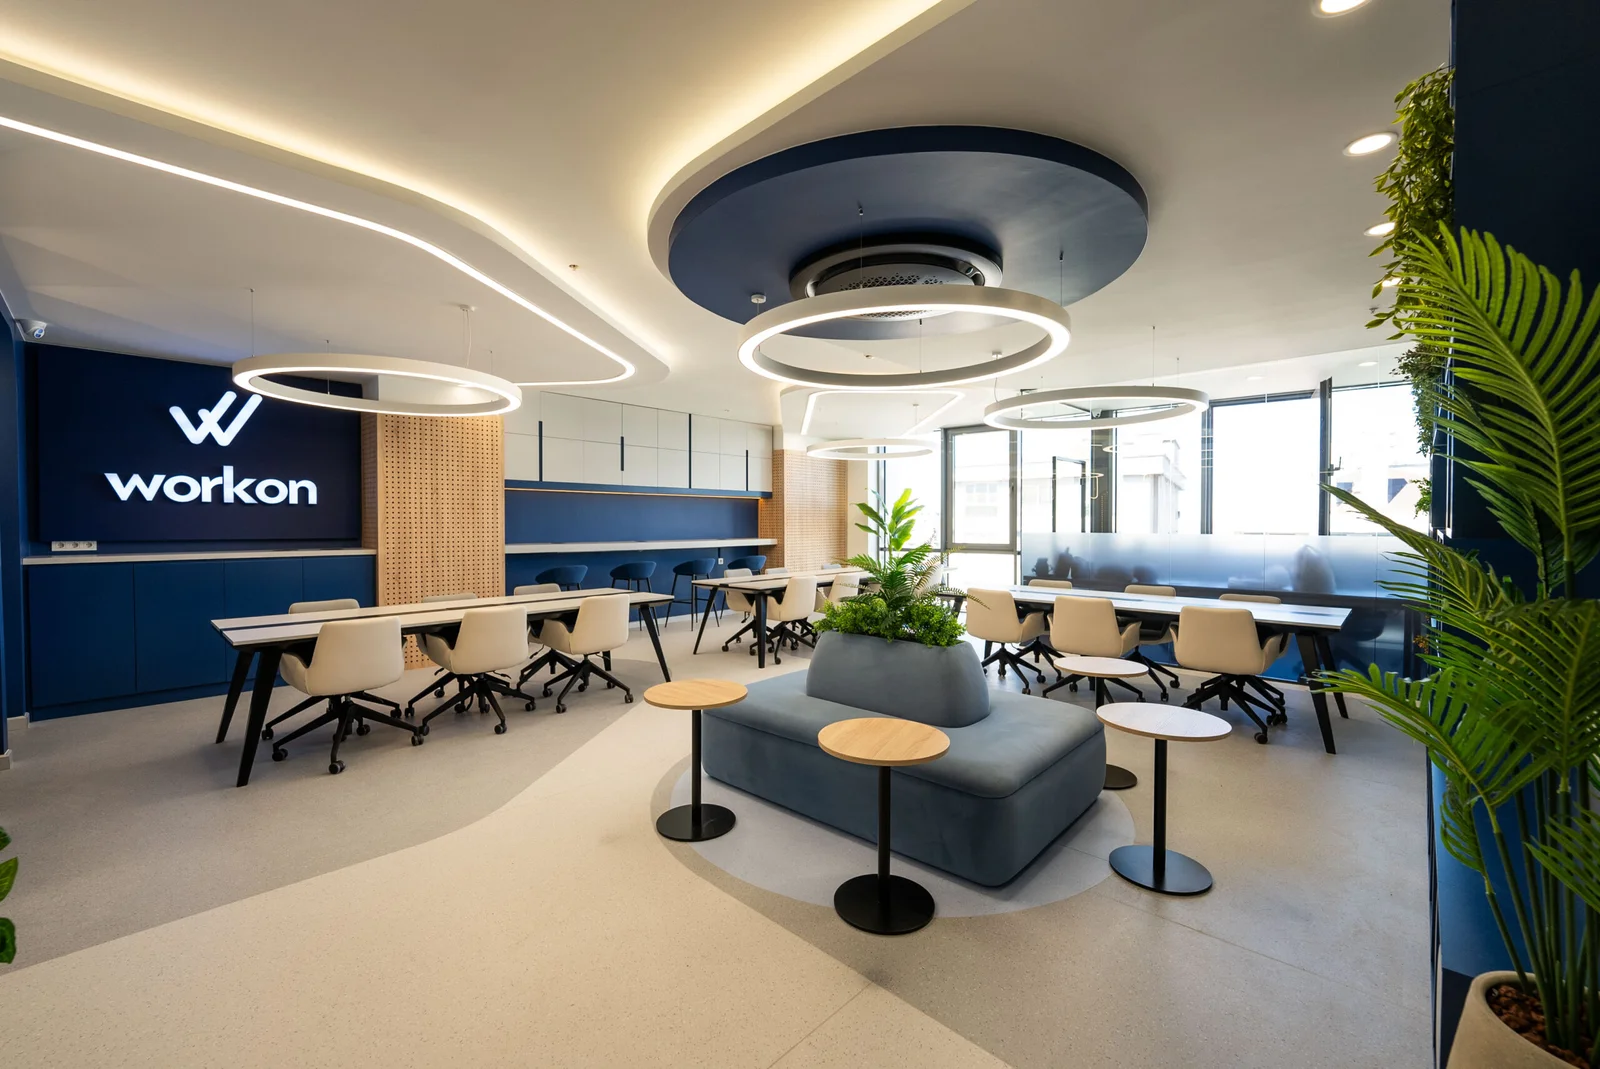
Virtual Office
Virtual Office in Turkey Workon provides virtual office and registered business address solutions in Istanbul […]
Details
Establish Company
Company Formation Coordination in Turkey Workon coordinates company setup in Turkey for foreign founders and […]
Details
Bank Account Application
Corporate Bank Account Application Support in Turkey Corporate banking is separate from company registration, and […]
Details
Nominee Services
Independent Company Representative Coordination in Turkey Workon helps international companies identify and coordinate the appointment […]
Details
Export License
Export Registration & Trade Coordination in Turkey There is no single universal export licence that […]
Details
Residency & Work Permits
Work & Residence Permit Coordination in Turkey Workon coordinates work and residence permit workflows for […]
Details
Landline Services
Business Landline & Call Management Services in Turkey Workon provides business landline and call-management solutions […]
Details
Trademark Registration
Trademark Application Coordination in Turkey Workon coordinates trademark-application workflows for founders and companies seeking protection […]
Details
Citizenship
Citizenship Application Coordination in Turkey Workon coordinates selected administrative steps for clients exploring Turkish citizenship […]
Details
Customs Process Advisory
Customs Process Coordination in Turkey Workon coordinates the business, document and provider handoffs surrounding import […]
Details
Recruitment Services
Recruitment Coordination in Turkey Workon coordinates recruitment support for companies building or expanding a team […]
Details
Procurement Services
Procurement Coordination in Turkey Workon coordinates supplier research and procurement workflows for companies sourcing products […]
Details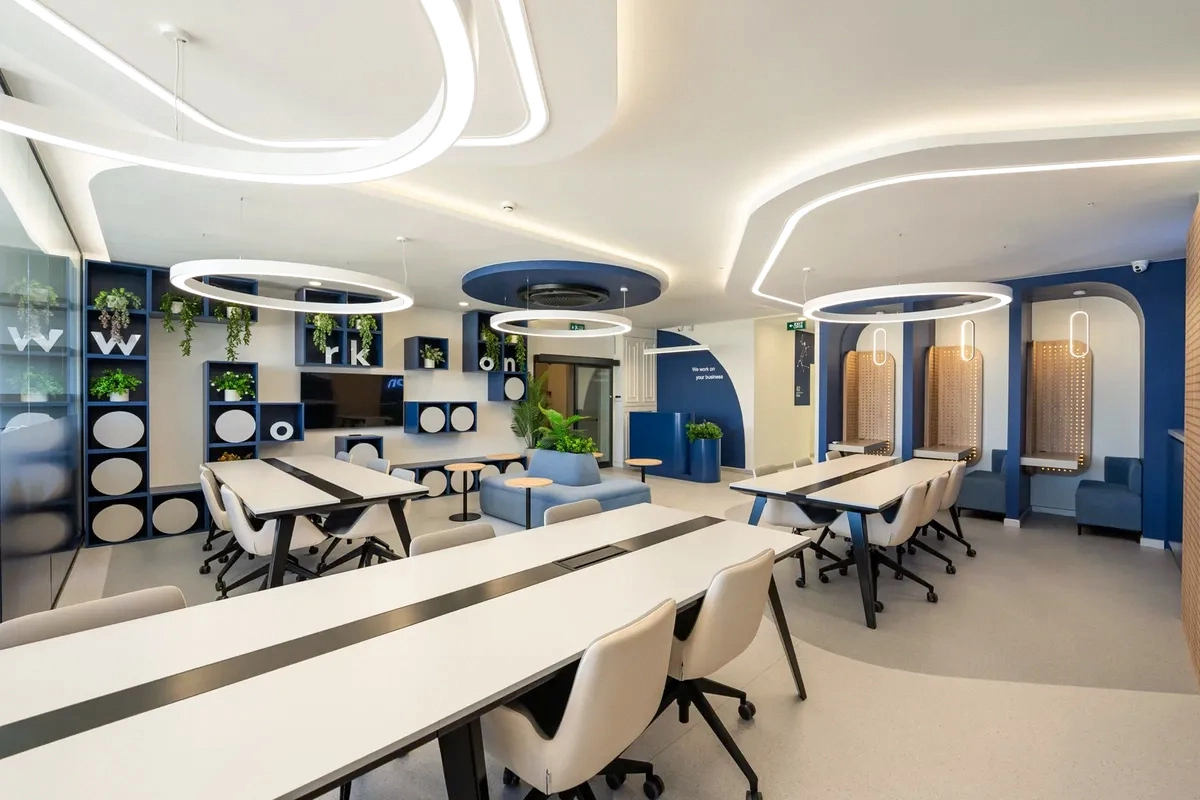
Coworking Offices
Coworking Offices in Istanbul Workon provides flexible coworking workspace in Ataşehir and Ümraniye for founders, […]
Details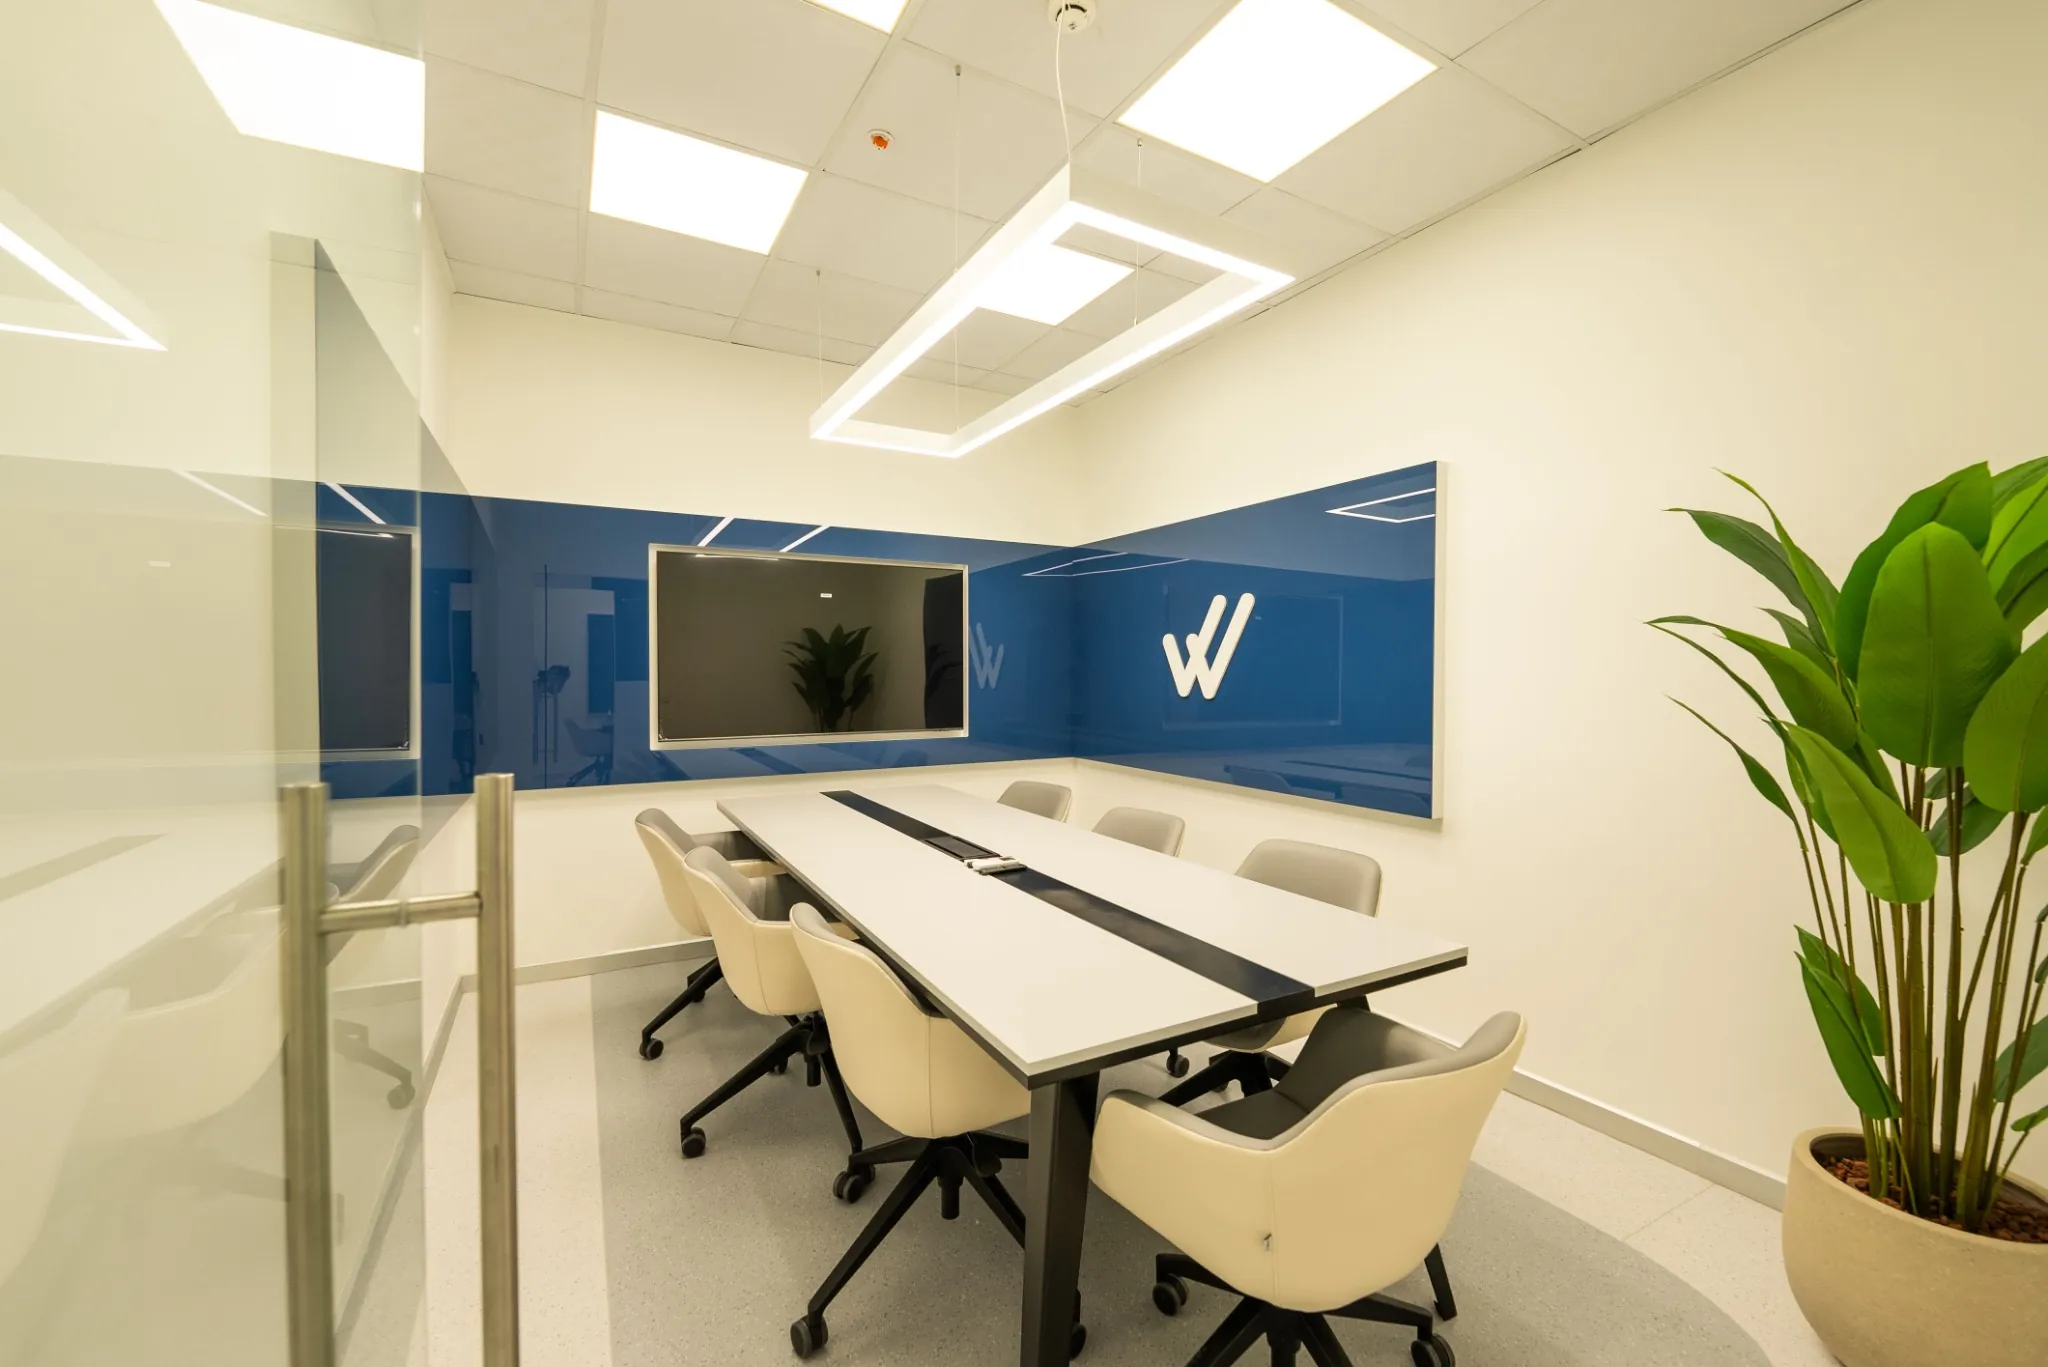
Meeting Rooms
Meeting Rooms in Istanbul Workon provides equipped meeting rooms in Ataşehir and Ümraniye for client […]
Details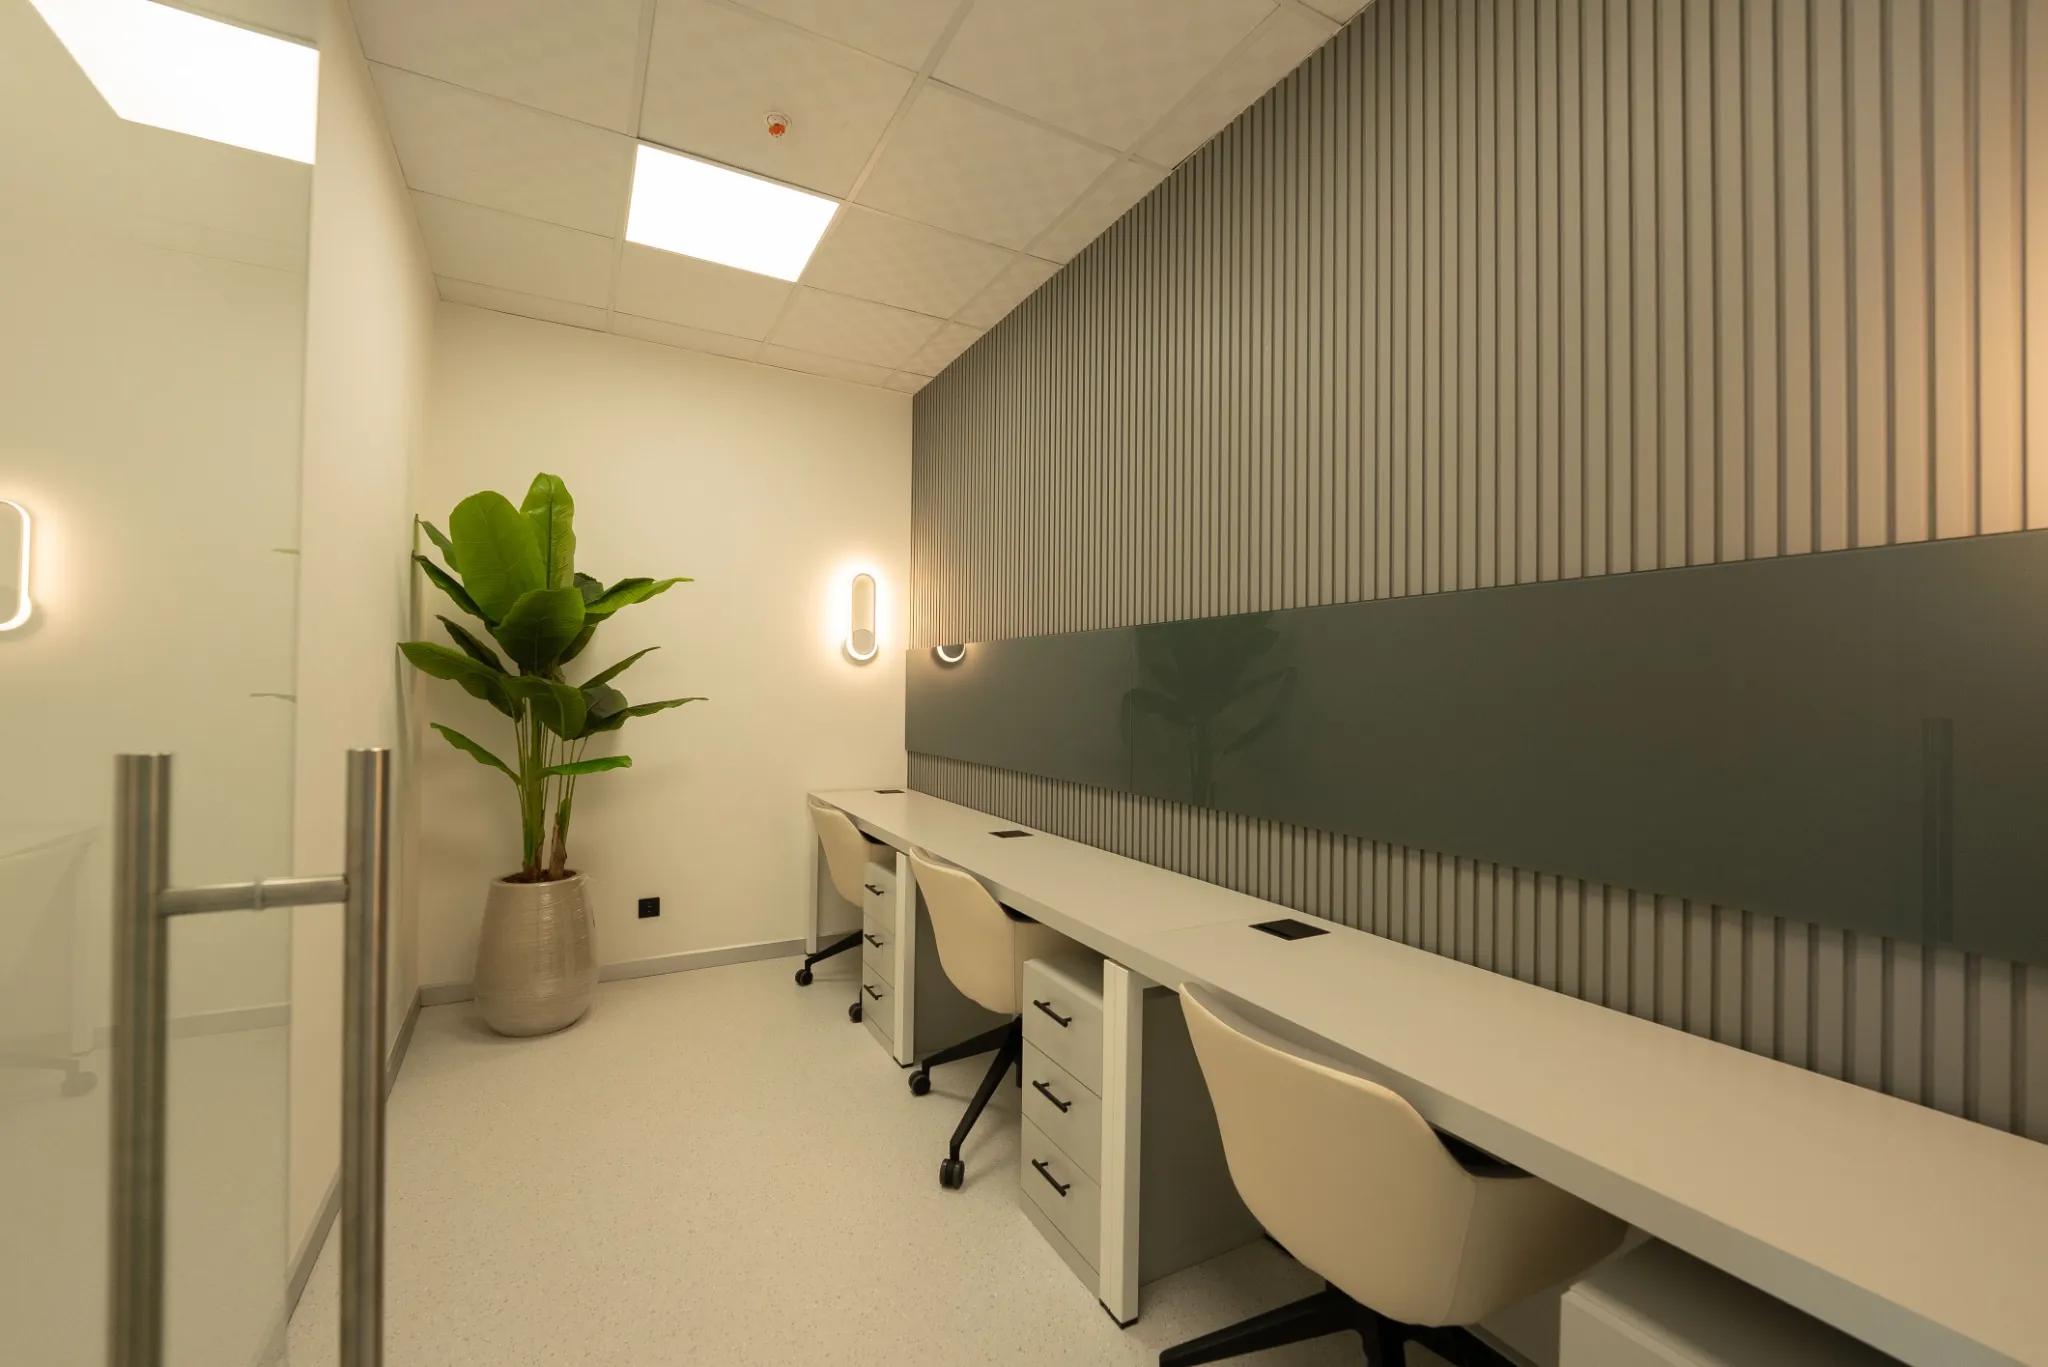
Private Offices
Private Offices in Istanbul Workon provides furnished private and serviced offices in Ataşehir and Ümraniye […]
Details
DUNS Number Application
D-U-N-S Number Application Support in Turkey The D-U-N-S Number is a unique nine-digit business identifier […]
Details
Mobile App Incentive Consulting
Mobile App Incentive Support in Turkey Reduce Your International App Growth Costs with Turkish Government […]
Details
-
-
- Contact Contact