Virtual Office for Freelancers in Turkey: Sole Proprietorship vs Company Address Guide 2026
24.08.2026
“Freelancer” is not a single legal or tax form in Turkey. Before choosing a virtual office, a person working independently needs to determine how the activity will be treated: for example as an individual commercial activity, a serbest meslek (self-employed professional) activity where applicable, or through a company such as an LLC.
The address decision comes after that classification. A home address, virtual/serviced office or dedicated premises can each be workable in the right case, but the registration route, documents and ongoing tax obligations are not identical.
This guide explains the freelancer business-form + address-suitability decision. It does not assume that every freelancer is a şahıs işletmesi, and it does not treat a virtual office as a legal requirement.
Turkey’s tax rules distinguish different taxpayer categories. GİB’s commencement guidance separately refers to taxable traders/artisans, self-employed professionals (serbest meslek erbabı) and corporate taxpayers. The correct route therefore depends on the actual activity and structure, not the label “freelancer.”
Possible structure
What to decide before the address
Individual commercial activity
Whether the activity is treated as commercial income and what registration, invoicing and bookkeeping obligations apply.
Serbest meslek activity
Whether the work falls within self-employed professional income rules and what taxpayer/document obligations apply.
Limited company or other company
Whether a separate legal entity better fits liability, ownership, hiring, investment, contracting or growth plans.
Have the activity classification confirmed before signing a long address contract. A licensed CPA/tax professional responsible for the actual registration should determine the tax route for the individual facts.
For an independent professional, choose the tax/business form first and then match the address model to that structure and activity.
A Virtual Office Is an Address Option, Not a Business Form
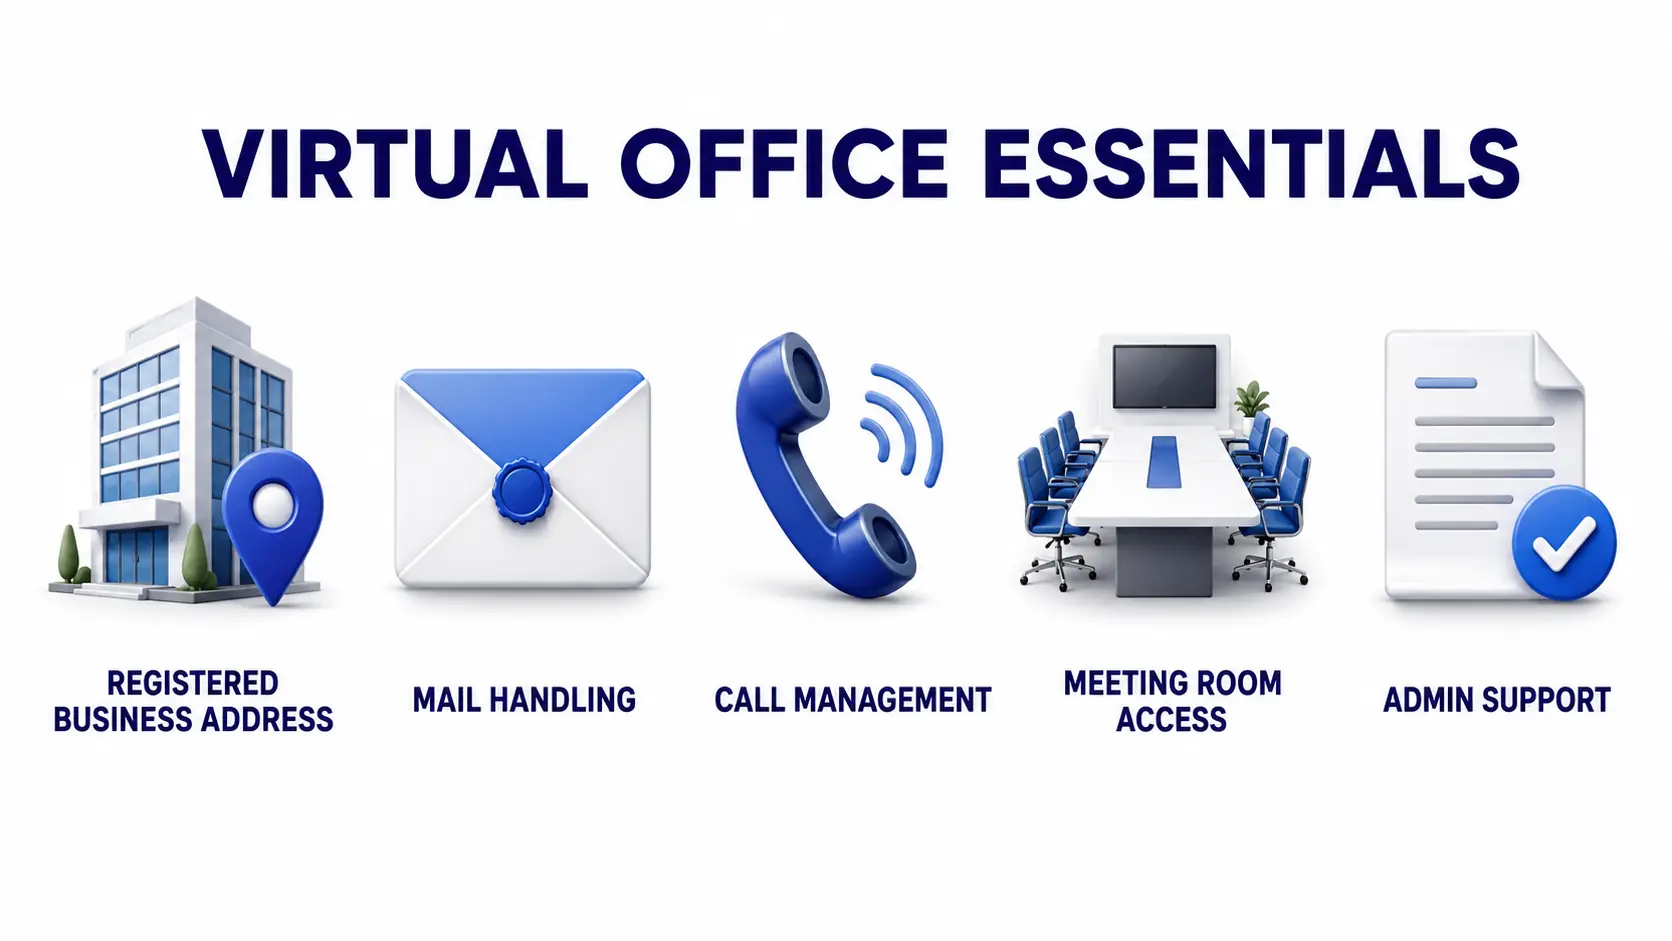
A virtual or serviced office can provide a business-address and administrative-service layer. It does not itself create a sole proprietorship, self-employed-professional status or limited company.
Where the arrangement is suitable, the service can provide:
a documented business/registered-address right;
receipt and handling of correspondence;
meeting-room or occasional workspace access;
reception or communications services depending on the package; and
a premises-side contact process for address-related authority requests.
Whether the exact address can be used in the taxpayer/company file depends on the chosen structure, premises, right-of-use documents and actual activity.
A virtual office is a service bundle; the legal and tax status of the freelancer is determined separately.
Address Options for an Independent Professional
Address model
When it may fit
What to verify
Home address
Remote work with limited physical operating needs where the property arrangement and activity are compatible.
Ownership/tenancy rights, contract/building restrictions, privacy, customer/staff use and any activity-specific premises requirements.
Virtual / serviced office
Independent work that does not require dedicated daily premises but needs a documented business address and mail process.
Exact address right, provider authority, mail handling, activity fit and the tax/company registration route.
Dedicated office
Regular client visits, staff, equipment, inventory or premises-sensitive work.
Lease/ownership file, operating cost and any municipal or sector-specific premises requirements.
Do not assume a home address is automatically invalid or a virtual office is automatically superior. The right answer depends on the property, activity, privacy preferences and registration route.
When a Virtual Office Is Often a Practical Fit
A virtual or serviced address can be practical for many remote-first independent activities where the work is performed online, at client sites or from changing locations and the business does not need dedicated operating premises.
Examples may include some consultants, developers, designers, writers, marketing specialists and other service professionals. These are examples only; the tax classification and premises suitability should be checked for the actual activity.
When a Virtual Office May Not Be Enough
Review additional or dedicated premises if the activity involves:
regular employees working at the business location;
frequent walk-in customers;
inventory, warehousing or fulfilment;
production, workshop activity or equipment;
health, food, education or another premises-sensitive service; or
a municipal, professional or sector-specific licence tied to physical premises.
The address model should reflect the real operation rather than being chosen only to complete a form.
Home Address vs Virtual Office for Freelancers
The strongest reasons to choose a virtual office over a home address are usually operational rather than legal slogans:
Issue
Home address
Virtual / serviced office
Privacy
The residential location can become part of business records/documents where applicable.
Keeps the commercial address separate from the founder’s home.
Mail process
The individual manages receipt directly.
Provider can receive, log and forward correspondence under the service agreement.
Client meetings
May require a separate venue.
Meeting rooms may be available depending on the package.
Property restrictions
Lease/building/co-owner or activity conditions may need review.
Provider-side premises and right-of-use conditions need review.
Fixed cost
Can be lower if the home setup is already suitable.
Adds a service fee but can avoid a dedicated lease.
Do not describe landlord consent, building-management consent, notarisation or a particular tax treatment as universal for every home-office case. Those questions depend on the actual property, contract and taxpayer.
If You Operate as a Serbest Meslek Professional
GİB’s current guidance treats serbest meslek erbabı as a distinct taxpayer category. Its published guidance states that commencement should be notified within the applicable statutory period and that address/workplace changes must also be reported within the required period.
Do not assume that working independently automatically makes the income serbest meslek income. Have the actual activity classified first, then confirm the address and registration documents for that taxpayer.
A single-shareholder LLC is a separate legal entity; it should not be described as the same thing as an individual/sole-proprietor registration. The company has its own registered headquarters and corporate/tax file.
A suitable business address is one input into the registration/compliance process. It does not by itself determine:
income-tax or corporate-tax treatment;
VAT obligations;
e-document/e-invoicing requirements;
bookkeeping and declaration duties;
social-security obligations;
sector licences; or
bank-account approval.
The selected business form and activity determine which of those workstreams apply.
Tax-Office Yoklama Can Apply to Individual Taxpayers Too
GİB’s current commencement guidance explains that the Electronic Yoklama System is used for taxpayer verification and sets administrative completion periods for different commencement cases. Do not convert that into a promise that every freelancer will receive the same physical visit or that a provider can guarantee the outcome.
If a virtual/serviced address is used, keep the right-to-use file, taxpayer details and activity explanation consistent and make sure the provider has a clear premises-side contact process.
Foreign Freelancers: Keep Residence and Work Permission Separate
A business or registered address is not automatically a personal residential address and does not itself create a residence or work permit. Foreign nationals should treat immigration/work-authorisation questions as a separate file based on their actual status and activity.
Likewise, owning or operating a Turkish business does not automatically determine the individual’s tax residency or cross-border tax position.
Freelancer Address Decision Checklist
Before registering, align the activity classification, taxpayer/business form and address documents.
Classify the activity. Is it commercial activity, serbest meslek activity or better operated through a company?
Choose the structure. Confirm the individual/company tax and legal route before buying the address.
Check premises needs. Does the work require customers, staff, equipment, stock or a licensed physical location?
Compare home vs virtual vs dedicated. Include privacy, mail, meeting use and property restrictions.
Validate the address file. Confirm the exact premises and right of use for the chosen registration route.
Plan tax registration and invoicing separately. The address service does not replace those steps.
Define official-mail handling. Know who receives and acts on time-sensitive correspondence.
Reassess when the business grows. Staff, customers, equipment or licensing can change the right premises model.
Common Mistakes
The biggest address mistake is choosing a premises model before the activity and taxpayer structure are clear.
Calling every freelancer a sole proprietor: tax classification depends on the real activity.
Buying the address first: determine the business/tax form and premises needs before signing.
Treating a virtual office as mandatory: home or dedicated premises may also be workable.
Assuming the address completes compliance: tax registration, invoicing, filings and licences are separate.
Using generic home-office rules: review the actual lease/property, building and activity conditions.
Ignoring official correspondence: define a receipt and escalation process from day one.
Mixing business and personal residence files: company/taxpayer address and immigration residence requirements are separate.
Workon coordinates registered-address, company-setup and workspace services for foreign founders and independent professionals.
If a virtual or serviced address fits your activity and chosen business form, review Workon’s virtual office service in Turkey. Current pricing and package inclusions belong on that live commercial page.
Frequently Asked Questions
Yes. First have the actual activity classified for the appropriate individual commercial, serbest meslek or company route. 'Freelancer' is not a single legal or tax category. Then check the address evidence and premises needs for that structure with the licensed professional handling registration.
No. It is an address and administrative-service option, not a business form or universal requirement. A home address, virtual or serviced office, or dedicated premises may fit depending on the activity, property rights, registration route and operating needs.
Compare privacy, correspondence handling, client-meeting needs, property restrictions, the right to use the exact address and total cost. Do not assume that a home address is automatically invalid or that a virtual office is automatically suitable for every activity.
Review the premises model when the work involves regular on-site staff, walk-in customers, stock, production, equipment or a premises-linked professional or sector requirement. The address arrangement should reflect how the business actually operates.
No. The address service does not itself establish taxpayer status, decide invoicing or bookkeeping duties, approve banking, or grant residence or work permission. Keep those workstreams separate and confirm the applicable requirements for the individual's activity and status.
General information only. Freelancer/self-employed classification, taxpayer registration, registered-address evidence, tax-office verification, invoicing, immigration and premises requirements depend on the individual activity and current rules. Confirm tax/legal classification and regulated matters with the relevant authorities and appropriately licensed professionals.
Subscribe to Newsletter
Be notified of the latest news in the business world quickly