Turkey’s 2026 incentive landscape for software, SaaS and IT companies is broader than a single advertising rebate. Under Presidential Decision No. 10962, eligible Türkiye-based technology companies can access different service-export support routes for areas such as workforce development, software licences, hosting, reports and databases, while separate tax and Technopark regimes may also be relevant depending on the company’s activities.
For foreign founders, the key is to separate these regimes instead of combining them into one headline “tax-free” or “cashback” promise. Eligibility, rates, annual limits, approved lists and application timing vary by support item, and applications under Decision No. 10962 are now handled through the Ministry of Trade’s DYS system.
Quick 2026 view: software and IT companies should first determine which regime applies to each cost or income stream: service-export support under Decision No. 10962, tax rules for qualifying export income, or a separate Technopark / technology-development-zone regime. Mobile app and digital game promotion and platform-commission support are covered in a dedicated Workon guide to avoid mixing app-specific rules into this broader software incentives page.
Last checked: 17 September 2026. Current Ministry annexes, approved lists and tax rules should be checked before a company commits expenditure or relies on a support in its financial plan.
Tax Rules for Software and IT Service Exports
Tax treatment is separate from Ministry of Trade cash-support programmes and should be analysed on its own facts.
Türkiye’s general corporate income tax rate for ordinary companies is 25% in 2026. For tax periods beginning on or after 1 January 2026, Presidential Decision No. 11257 increased the deduction rate under Article 10/1-(ğ) of the Corporate Tax Law to 100% for qualifying income covered by that provision.
That does not mean every software or SaaS company in Türkiye automatically pays 0% corporate tax. The statutory conditions still matter, including the nature of the service, the foreign customer, where the service is used, invoicing and transfer of the relevant revenue to Türkiye. Minimum corporate tax and other tax rules may also affect the final position.
For that reason, Workon treats tax eligibility and Ministry incentive eligibility as two separate questions. The tax position should be confirmed with a licensed Turkish CPA or tax adviser before it is built into a financial model.
See the Revenue Administration’s explanatory note on Presidential Decision No. 11257.
Mobile App and Game Incentives: Use the Dedicated 10962 Guide
Mobile applications and digital games have support routes under Decision No. 10962 that require their own eligibility, product, platform and expenditure analysis. App publishers should check user-acquisition spending and platform commissions against the rules for their specific product and sales model, rather than treating them as general software-company expenses.
For current digital product promotion rates, platform commission limits, target-country rules, DYS workflow and foreign-owned app company eligibility, see Workon’s 2026 Mobile App Incentives in Turkey guide under Decision No. 10962.
Simplify your business setup with Workon’s all-in-one company registration service in Turkey.
Why the separation matters: older online articles may still show USD-denominated app limits, blanket 60%–70% promotion rates or fixed reimbursement timelines from the previous framework. Those figures should not be reused for a 2026 application. Use the mobile-app guide to check the product-specific limits and application requirements before committing app or game expenditure.
Key 2026 Support Routes for Software and IT Companies
Under the 10962 framework, software and IT companies should map each cost to the exact support item rather than relying on old USD-denominated package summaries.
| Support Route |
2026 Base Support |
Key Limit / Note |
| Workforce Development |
50% |
For qualifying international promotion and marketing roles in Türkiye: up to 5 employees at the same time, up to TRY 90,000 per employee per month, for up to 5 years. |
| Hosting |
50% |
Up to TRY 5 million per year per beneficiary, for up to 5 years. |
| Software Licence |
50% |
Up to TRY 2.5 million per year per beneficiary, for up to 5 years; current Ministry-supported software lists and rules apply. |
| Reports and Databases |
50% |
Up to TRY 2.5 million per year per beneficiary, for up to 5 years; current approved lists and application rules apply. |
The Ministry’s current sectoral support index also includes other support items, but not every item applies to every software company. See the current Ministry of Trade sectoral support items and annexes before planning expenditure.
Which incentive route should you check first?
- Exporting software or IT services to foreign customers? Review the service-export tax conditions separately from Ministry reimbursements.
- Hiring staff for international promotion and marketing? Check the 10962 workforce-development route and current personnel qualifications.
- Paying for hosting, software licences, reports or databases? Match each expense to its dedicated support item and current approved lists.
- Building an R&D or software project inside a Technology Development Zone? Evaluate Technopark rules as a separate regime.
- Publishing a mobile app or game with international user-acquisition or platform commissions? Use the dedicated mobile-app incentive guide rather than this general software page.
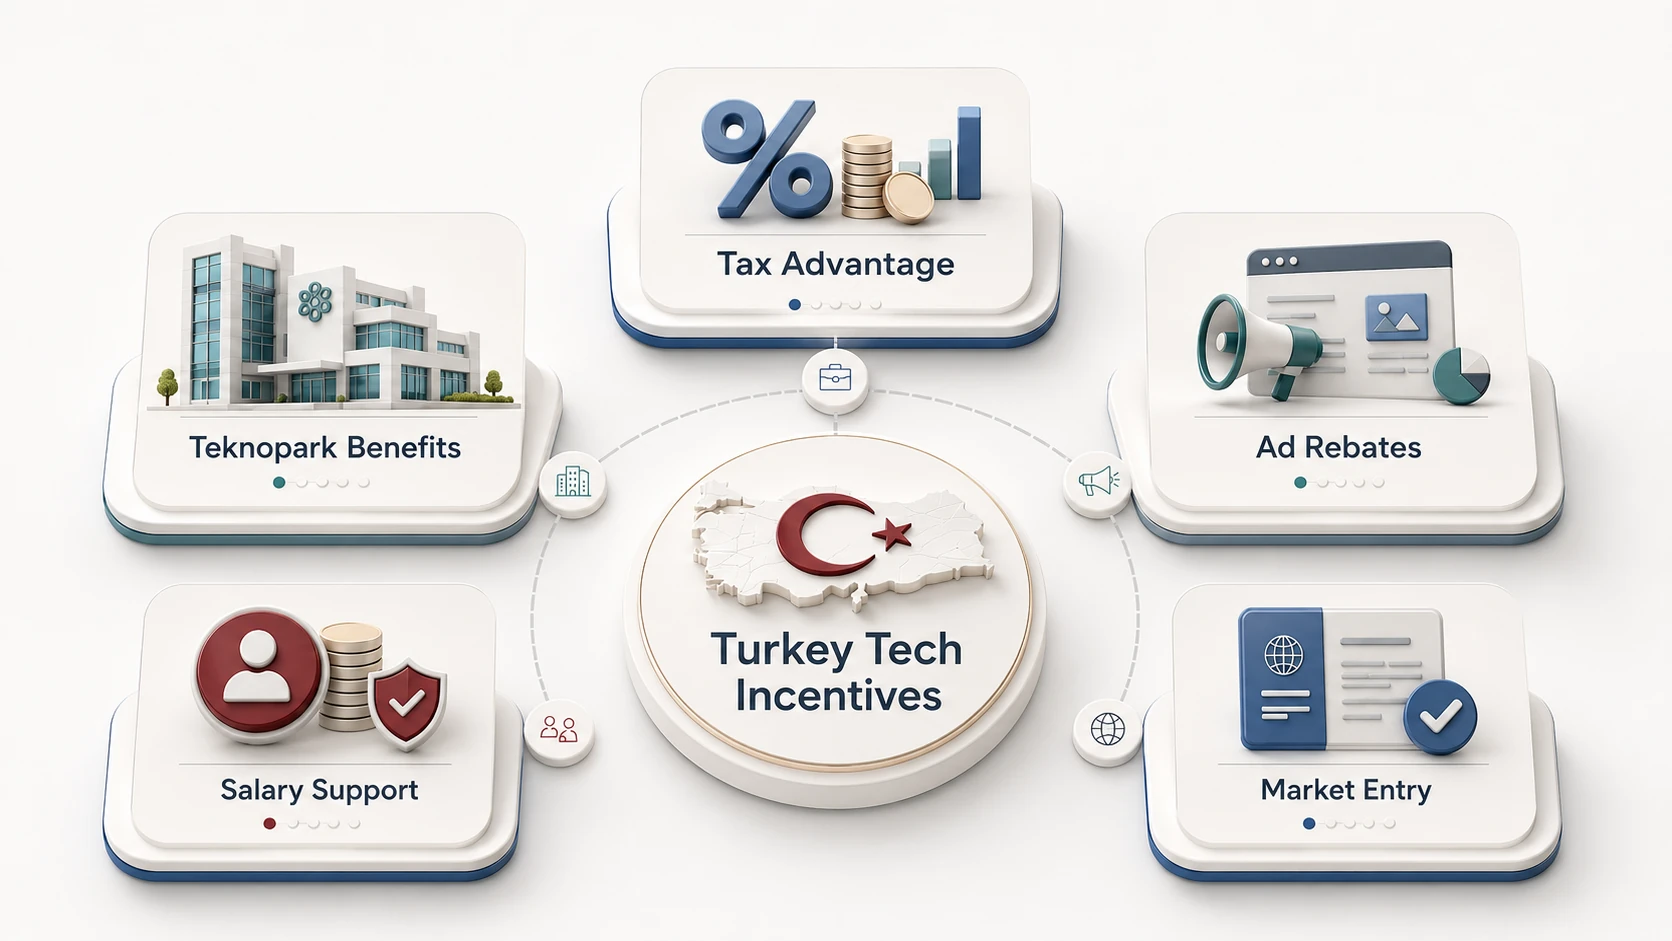
Software and IT companies should evaluate service-export supports, tax rules and Technopark incentives as separate regimes.
Workforce Development Support for International Growth
Decision No. 10962 includes a workforce-development support route for beneficiaries in the IT sector that employ staff in Türkiye for international promotion and marketing activities.
For qualifying domestic employees, eligible employment expenses are supported at 50%, for up to 5 employees at the same time, with support of up to TRY 90,000 per employee per month. Each beneficiary can use this support for up to 5 years.
The Decision also provides a separate route for qualifying employees working in eligible overseas units, with different limits. The Ministry determines the required employee qualifications, so companies should check the current personnel-qualification annex before hiring or treating a salary as support-eligible.
This is materially different from older guidance referring to a 10-person limit, a blanket six-month hiring condition or generic diploma and language-certificate requirements. Use the current 10962 rules and Ministry annexes rather than carrying forward those older assumptions.
Technopark Incentives Are a Separate Regime
Technology Development Zones (commonly called Technoparks or Teknoparks) can be relevant to software and R&D companies, but they should not be presented as part of the same support calculation as Decision No. 10962.
Technopark benefits depend on the company’s approved project, the activities carried out within the zone and the applicable technology-development-zone legislation. Tax, payroll and social-security consequences can vary by activity and employee, so they should be checked separately from Ministry of Trade service-export reimbursements.
A foreign-owned software company does not need to assume that it must enter a Technopark before it can operate in Türkiye. In practice, some founders first establish the company and operating structure, then assess whether a qualifying R&D or software project justifies a separate Technopark application.
For choosing a zone and preparing a project application, use the Technopark admission guide. For the tax and payroll treatment after acceptance, use the Technopark R&D incentives guide. The official framework and current zone information are available through the Ministry of Industry and Technology’s Technopark portal.
What Foreign-Owned Software Companies Should Check Before Applying
For foreign founders, the main difficulty is usually not company ownership itself but keeping the beneficiary, contracts, invoices, banking records, software or service activity and application documents aligned with the current support rules.
Before relying on an incentive in a budget, check:
- Beneficiary status: which Türkiye-based company will apply and whether it fits the relevant sector and support definition.
- Service-export structure: who the foreign customer is, where the service is used and how the income or supported activity is documented.
- Expense mapping: whether the cost belongs to workforce development, software licence, hosting, reports/databases or another current support item.
- DYS readiness: whether beneficiary registration and the applicable forms and annexes are complete.
- Payment trail: whether contracts, invoices and payment evidence consistently identify the beneficiary and supported activity.
Applications under Decision No. 10962 are received through DYS (Destek Yönetim Sistemi / Support Management System). KEP remains a separate official communication infrastructure in Türkiye, but older guidance describing KEP as the sole application channel should not be used for the current 10962 process. See Workon’s KEP guide for foreign-owned companies and the Ministry’s current DYS application announcement.
How Workon Supports Foreign Software and IT Companies
Workon can coordinate the operational steps that sit around an incentive application: establishing the Türkiye-based company, arranging a registered business address, coordinating corporate bank-account applications, organising the documentation flow and helping the company prepare for the relevant DYS process.
For a foreign software or SaaS company, the practical value is having the company structure, payment trail and support documentation considered together before major expenditure is committed. If you are still at the setup stage, see Workon’s company registration in Turkey service.
Workon does not guarantee that an application will be approved or that a particular tax treatment will apply. Where regulated legal, tax or accounting advice is required, the relevant position should be handled or confirmed by licensed professionals. Technopark admission and benefits should likewise be assessed under the separate rules of the relevant zone and project.
Build the Right Incentive Map Before You Spend
The most useful first step is not to assume that one programme covers every software-company cost. Separate your planned expenditure and income into the relevant buckets: service-export support, tax treatment, Technopark rules and app/game-specific support where applicable.
If you are a foreign founder or international software company considering Türkiye, Workon can coordinate the company-setup and operational preparation needed before an incentive application is assessed.
For a more useful first review, include your software or SaaS activity, Turkish company status, target markets, expected payroll and software/hosting expenditure, and whether you already have DYS registration. Contact Workon to discuss your software or IT incentive-readiness needs.
Frequently Asked Questions
The main families should be assessed separately: Ministry of Trade service-export support under Decision No. 10962, tax treatment for qualifying export income, Technology Development Zone or Technopark incentives, and app or game-specific support where relevant. One company can have different rules for different income and cost streams.
No. The article notes that the Article 10\/1-(ğ) deduction rate was increased to 100% for qualifying income for tax periods beginning in 2026, but the statutory conditions still matter and minimum corporate tax or other rules can affect the result. It is not a blanket 0% corporate-tax regime for every software or SaaS company.
Depending on the support item and current Ministry rules, eligible companies can assess routes such as workforce development for international promotion and marketing, hosting, software licences and approved reports or databases. Rates, caps, lists, timing and documentation are support-specific.
Potentially yes. Foreign ownership alone does not automatically disqualify the Turkish beneficiary, but eligibility depends on the company, activity, export or cost item, contracts, invoices, payment trail, current programme conditions and DYS documentation.
No. Technology Development Zone incentives are a separate legal and tax regime tied to the approved project, qualifying activity, personnel and zone rules. They should be evaluated independently rather than combined into one generic software-incentive percentage.
They fall within the current service-export support architecture but have app and digital-product-specific eligibility, product, platform and expenditure rules. The article intentionally routes those details to the dedicated 2026 mobile-app incentive guide instead of applying a generic advertising-rebate claim to every software company.