Company Formation in Turkey: Complete 2026 Guide for Foreigners
21.07.2026
Quick answer: Foreign individuals and overseas companies can generally establish and own a company in Türkiye without a Turkish shareholder. The right route depends on the planned activity, shareholder type, governance needs and whether the founder must complete any part of the process remotely.
Company registration creates the legal entity. It does not, by itself, make the business ready for banking, invoicing, employment or a regulated activity. This 2026 guide separates the Trade Registry stage from the operational steps that follow.
Foreign founders most often compare a limited liability company (LLC), a joint-stock company (JSC), a Turkish subsidiary owned by an overseas company and a branch of an overseas company. The decision should follow the intended ownership and operating model, not the label that sounds most established.
Route
Often considered when
Important points
Limited liability company (LLC)
An owner-managed business, SME, agency, consultancy or trading company needs a separate Turkish legal entity
One to 50 shareholders; minimum statutory capital is TRY 50,000; governance is generally leaner than a JSC
Joint-stock company (JSC)
The business expects outside investment, different share groups, formal governance or a structure familiar to institutional counterparties
Minimum statutory capital is TRY 250,000; at least 25% of cash capital is generally paid before registration and the balance within two years
Turkish subsidiary
An overseas company wants a separate Turkish entity under corporate ownership
The parent-company resolutions, current-status records and signatory documents must be prepared for use in Türkiye
Branch
An overseas company wants to operate in Türkiye without forming a separate legal entity
The branch remains linked to the parent, operates within the parent’s purpose and requires an authorised resident representative
Minimum Capital Is Company Money, Not a Formation Fee
Statutory share capital is not a Workon fee, professional fee or government charge. It is money committed by the shareholders to the company. Quotations should show capital separately from provider fees, official payments, professional work and document expenses.
Item
Legal amount or basis
How to read it
LLC minimum capital
TRY 50,000 (approximately EUR 892)
Company capital; the LLC pre-registration 25% cash-payment rule does not apply, and subscribed capital may generally be paid within 24 months
JSC minimum capital
TRY 250,000 (approximately EUR 4,457)
Company capital; at least 25% of cash capital is generally paid before registration and the balance within two years
Competition Authority payment
0.04% of capital
A separate statutory payment, not money retained as company capital
Service and professional fees
Based on the written scope
Workon coordination, licensed professional work and third-party costs must be identified separately
Registered-capital exception: if a non-public JSC adopts the registered-capital system, the current minimum starting capital is TRY 500,000. The TRY 250,000 figure above is the general minimum for an ordinary JSC.
The EUR figures use the TCMB foreign-exchange selling rate published for 28 August 2026 (EUR 1 = TRY 56.0853). They are dated comparisons only; the legal capital amounts remain denominated in TRY.
Workon coordinates company registration and connected operational steps according to the agreed written scope.
Documents for Individuals, Corporate Shareholders and Branches
The document list changes materially when the shareholder is a foreign company rather than an individual. It also changes again for a branch. Confirm the issuing country, signatories and intended Turkish use before arranging apostilles, consular legalisation or courier delivery.
Scenario
Core document categories
Home-country point
Foreign individual shareholder
Passport, potential tax number, address information, registry forms and, for remote coordination, a suitable power of attorney
Passport and power-of-attorney formalities depend on the country of issue and the way the documents will be used
Foreign corporate shareholder / subsidiary
Certificate of activity or current status, constitutional documents, authorised-signatory records, shareholder or board resolution, representative appointment and power of attorney
Documents normally require the applicable notarisation and apostille or Turkish consular legalisation route before sworn Turkish translation and notarisation
Branch of a foreign company
Parent-company resolution, constitutional documents, activity/current-status certificate, resident representative appointment and authority, establishment forms and signature documents
The parent prepares and obtains its corporate records in its own jurisdiction
The exact list depends on the registry, issuing country, shareholder chain, representation model and activity. Unless a written proposal expressly says otherwise, documents that an overseas shareholder or parent must obtain or prepare in its home country—and the costs incurred there—are outside the Workon package. Türkiye-based sworn translation, notarisation and legalisation handling are treated according to the written scope.
Company incorporation can generally be coordinated through a properly drafted power of attorney and correctly legalised documents. The authority must cover the acts required for the chosen structure; vague or incomplete wording can create a second document cycle.
Remote incorporation and remote corporate banking are separate matters. A company may be registered without every founder travelling, but a bank still performs its own compliance review of the company, shareholders, controllers, directors and intended transactions. Many banks require an authorised director to attend in person. A bank-specific remote process may sometimes be available, but approval and activation belong to the bank and cannot be guaranteed as part of Trade Registry incorporation.
Company Registration Process in Turkey
Define the structure: confirm the entity type, shareholders, managers or directors, registered address, capital, representation rules and planned activity.
Prepare shareholder documents: obtain the individual or corporate documents required for the chosen route.
Complete legalisation and translation: use the correct apostille or consular route and arrange sworn Turkish translation and notarisation where required.
Obtain potential tax numbers: non-Turkish shareholders and relevant managers or board members generally require potential tax identification numbers.
Draft through MERSİS: record the company name, purpose, capital, ownership and representation rules in the central registration system.
File with the Trade Registry: submit the accepted documents, make the statutory payments and complete registration.
Collect registration outputs: obtain the registry records and complete applicable signature and legal-book formalities.
A Trade Registry filing may be completed quickly after a complete and accepted file is ready. The end-to-end schedule still depends on overseas document preparation, legalisation, translation, appointments and institutional review. Banking, the tax-office commencement process, digital tools and sector approvals have their own timelines. No single duration accurately covers every founder’s route.
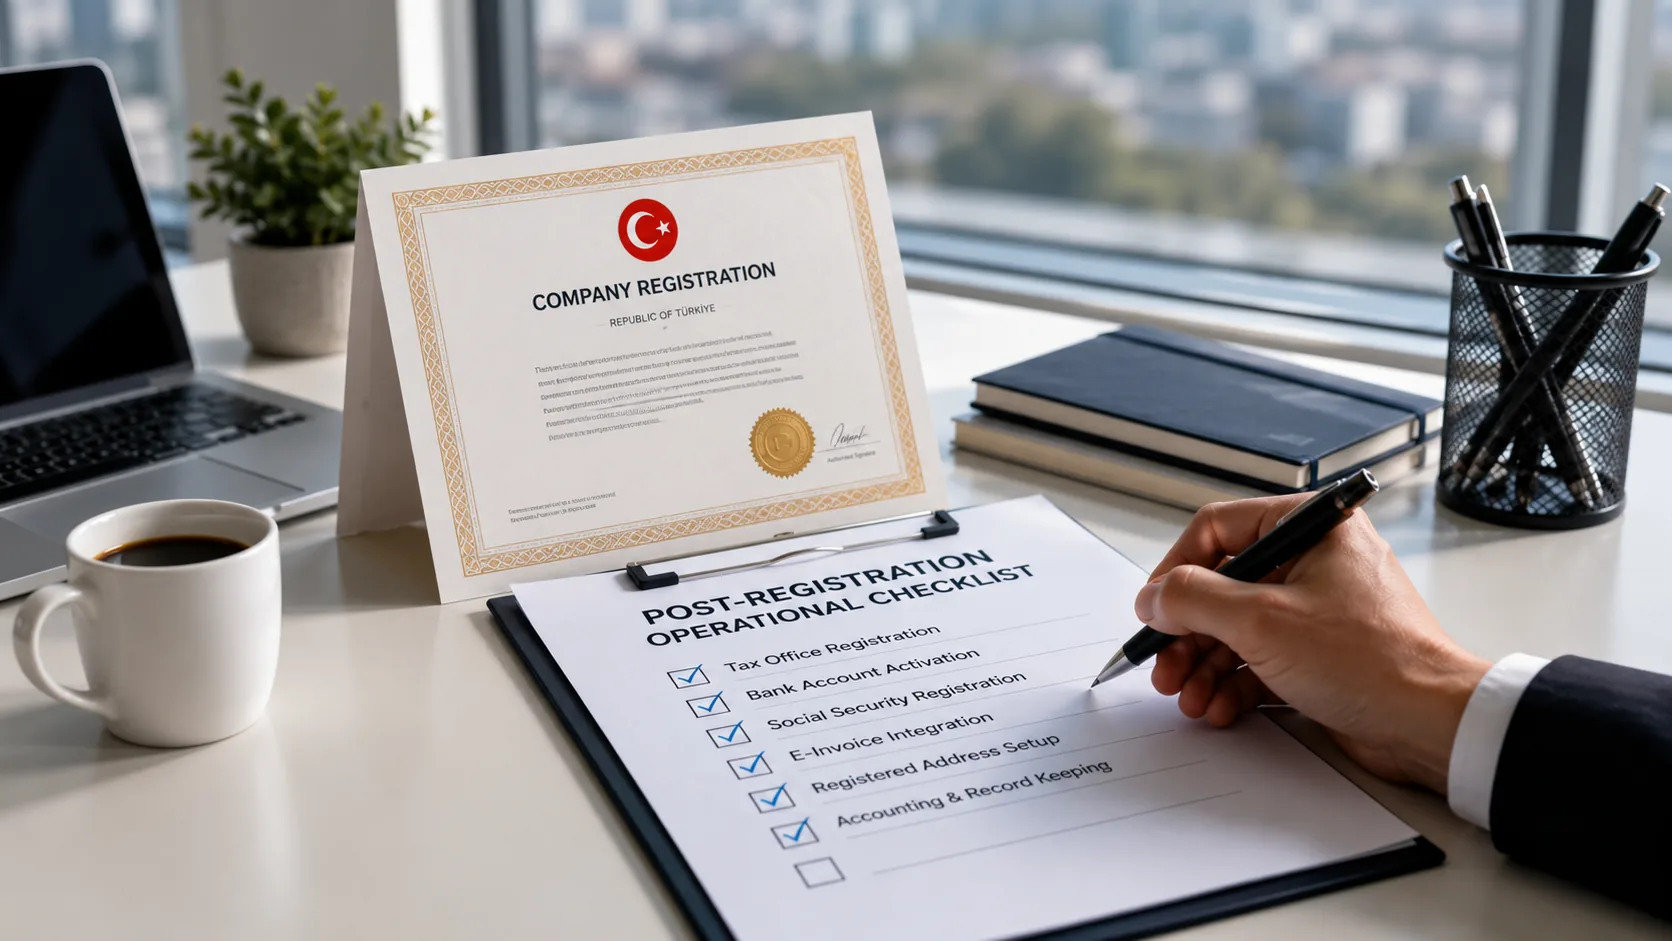
Registration and Operational Readiness Are Different Milestones
A registered company may still need tax, banking, address, digital and sector steps before it is ready to operate.
Milestone
What it means
Main dependency
Trade Registry registration
The legal entity or branch has been registered
A complete and accepted incorporation file
CPA and tax onboarding
Authorisations, filing responsibilities and the compliance calendar are organised
Engagement with a licensed Turkish CPA
Address verification
The tax-office commencement yoklama / verification process is prepared and coordinated
A suitable registered address, authorised contact and requested evidence
Bank application and usability
The bank assesses the entity, controllers and intended activity
The bank’s compliance approval; presence or a special remote procedure may be required
Digital and invoicing readiness
Applicable KEP, e-signature, financial seal and invoicing steps are completed
Entity type, activity, turnover and current authority requirements
Employment or sector readiness
Applicable SGK, licences, memberships or product registrations are in place
Employees, activity, products and operating model
Workon’s company-formation packages include preparation and coordination for the tax-office commencement inspection, including when the registered address is not a Workon office. The authority controls timing and outcome; coordination is not a tax audit and does not guarantee approval.
A registered address must be suitable for the company and its activity. A physical office is not automatically required in every case, and a virtual office in Turkey may be considered where the facts and current requirements allow it. Address suitability, tax-office procedures and sector conditions must be checked separately.
How to Compare Company Formation Costs
A single advertised total can hide exclusions. Compare written proposals against the same cost stack:
Cost layer
What to check
Workon coordination fee
The exact registration and operational-coordination work included in the proposal
Official payments
Trade Registry, chamber, Competition Authority and other statutory amounts
Licensed professional fees
CPA, legal, customs or other regulated professional work required by the case
Türkiye document costs
Sworn translation, notarisation, copies, courier and legalisation-related handling
Home-country costs
Corporate records, notarisation, apostille or consular legalisation and international courier arranged abroad
Capital
Shareholder funds committed to the company; not a provider or government fee
Operating costs
Registered address, licensed CPA, banking, digital tools, payroll and activity-specific requirements after registration
What the Istanbul CPA Tariff Can Tell You
The Istanbul Chamber of Certified Public Accountants (İSMMMO) publishes a 2026 workload-based professional fee tariff. It is a reference for licensed SMMM/CPA work—not a Workon price, public filing fee or universal quotation.
Selected 2026 İSMMMO tariff references relevant to company formation
Professional-service tariff row
Original TRY reference
Approximate EUR*
What it does not represent
Foreign-capital company establishment
TRY 25,450
EUR 454
Not share capital, Trade Registry/notary/translation costs or Workon’s coordination fee
Micro class 1 bookkeeping, 0–12 MB
TRY 7,985 per month before applicable adjustments
EUR 142
Not a final monthly quote; workload and tariff adjustments still apply
Corporate income-tax return
TRY 6,730
EUR 120
Not automatically an extra charge where the engagement and tariff notes treat the filing as included
*Approximate EUR amounts use the same 28 August 2026 TCMB rate stated above. The tariff notes include workload variables and additions or reductions for matters such as business scale, digital-ledger size, employees, İstanbul, branches, foreign trade, inflation adjustment and inactive status. The applicable professional scope must be confirmed by the licensed SMMM/CPA. See the İSMMMO professional fee tariff index and Workon’s detailed Turkish CPA guide.
Variable Türkiye translation and notary expenses are normally handled through an estimated budget and reconciled against actual cost. Fees for a licensed CPA vary with the activity, document volume, employees and filing obligations. For dated EUR examples and the full comparison method, read the true cost of setting up a company in Turkey and the Turkish CPA requirement guide.
Common Preventable Risks
Early checks reduce avoidable rework across documents, registration, banking and post-registration coordination.
Choosing a structure for appearance: compare ownership, governance, transfer, capital and investment needs before selecting an LLC or JSC.
Sending foreign documents too early: confirm wording, issuing authority, validity, legalisation and translation requirements before signatures or courier dispatch.
Using a narrow power of attorney: map the required acts before the document is notarised or legalised.
Treating registration as launch day: plan banking, CPA/tax onboarding, address procedures and digital requirements as distinct milestones.
Assuming bank approval: prepare source-of-funds, ownership and business-activity evidence, but recognise that the bank retains the decision.
Ignoring an inactive company’s obligations: a company may still have recurring filing and compliance duties even when it has no transactions. The licensed CPA should confirm the current calendar for the specific entity.
Video overview: This Workon video explains the company-setup journey for foreign founders. Bank, tax, permit and institution-controlled requirements should still be confirmed for the individual case.
How Workon Coordinates the Process
Workon is an end-to-end business setup and operational coordination platform for foreign founders and overseas companies entering Türkiye. Depending on the agreed scope, Workon coordinates the incorporation file, registered address, power-of-attorney and document workflow, Trade Registry steps, bank-application preparation, licensed CPA onboarding, tax-office commencement yoklama / verification preparation, KEP and e-signature, and connected operating requirements.
Where the agreed scope includes regulated legal, tax/accounting, customs, sworn-translation or notarial work, Workon coordinates the required handoff through the appropriately licensed or authorised professional. Banks and public authorities retain their own approval powers and timelines.
Last reviewed: 13 September 2026. Company structure, foreign-document formalities, banking and sector requirements should be confirmed for the specific shareholder, activity, issuing country and institution.
Frequently Asked Questions
Define the legal structure, shareholders, management and signing model, real business activity, registered address, capital plan, foreign-document route and the post-registration functions the business must actually use. Those decisions determine the correct filing and operational sequence.
Trade Registry registration creates the legal entity and its commercial-registry record. It does not by itself complete banking, licensed CPA and tax workflows, invoicing tools, employment, work permits or activity-specific licences.
Move the final company records into the tax and licensed-professional workflow, complete any address verification or follow-up, prepare corporate banking and digital tools, and activate employment, customs, licences or other operating requirements triggered by the real business model.
Subscribe to Newsletter
Be notified of the latest news in the business world quickly