Budget for company formation in Turkey in three parts: one-off setup expenses, the company’s own share capital and first-year operating costs. This 2026 guide separates service and professional fees, official payments, foreign-document costs and ongoing expenses so you can compare quotations on the same basis. Your total depends on the entity, shareholder profile, document requirements and agreed service scope. Share capital belongs to the company and is not a formation service fee.
Core legal and cost methodology rechecked: 17 September 2026. The EUR conversions below remain deliberately frozen to the article’s stated historical reference rate of EUR 1 = TRY 56.0853 on 28 August 2026 so the examples stay internally consistent rather than pretending to be current quotations. Statutory amounts remain identified in their original TRY denomination. Historical examples are converted at this same rate for consistent comparison, retain the original TRY figures, and are not current quotations.
A useful formation budget separates fees, capital and post-registration operating costs.
Company formation cost is not one number
Two founders can register companies in the same city and still receive very different quotations. A single-shareholder limited liability company formed by an individual generally requires a different document set from a Turkish subsidiary owned by a foreign company. A branch has another structure again.
| Scenario |
Main cost drivers |
Important scope point |
| Foreign individual shareholder |
Passport-related documents, translation and notarization, registered address, official registration steps and post-registration setup |
Usually the lightest document file, but nationality, residence and the chosen route may change the requirements |
| Foreign corporate shareholder or subsidiary |
Parent-company records, corporate resolutions, authority and signatory evidence, apostille or consular legalization, translation, notarization and courier |
Documents and costs arising in the shareholder’s home country are outside the Türkiye-side package unless the written quotation expressly includes them |
| Branch of a foreign company |
Parent-company constitutional and status documents, branch resolution, representative documents, legalization, translation, notarization and operating setup |
A branch is not an independent legal entity and its document file should not be compared with an individual-owned LLC quotation |
For the underlying structural differences, see Workon’s branch versus subsidiary guide and company-type comparison.

Workon coordinates company registration and the steps needed to move from incorporation toward operational readiness.
The seven parts of a transparent formation budget
A quotation is easier to compare when every payment has an identified recipient, purpose and timing.
| Cost category |
What it covers |
How to read it |
| Workon coordination fee |
Planning and coordination of the agreed incorporation and operational setup scope |
A service fee; it should state what is included and excluded |
| Official and pass-through costs |
Trade Registry, chamber, gazette and other applicable institutional payments |
Identify the institution, transaction and date rather than treating every amount as permanently fixed |
| Licensed professional fees |
Fees charged by an SMMM/CPA, lawyer, customs broker or another regulated professional where required |
Separate from Workon’s coordination fee and based on the professional’s engagement and scope |
| Türkiye document costs |
Sworn translation, notarization, certification, copies and courier inside Türkiye |
Usually document- and transaction-dependent |
| Home-country costs |
Corporate records, local notarization, apostille or consular legalization and international courier |
Not included unless the written offer expressly says so |
| Share capital |
Funding committed to the company |
Company money, not a service fee or government charge |
| Operating and sector costs |
Registered address, licensed CPA process, banking, KEP/e-signature, employees, permits and activity-specific requirements |
Depends on how the company will operate after registration |
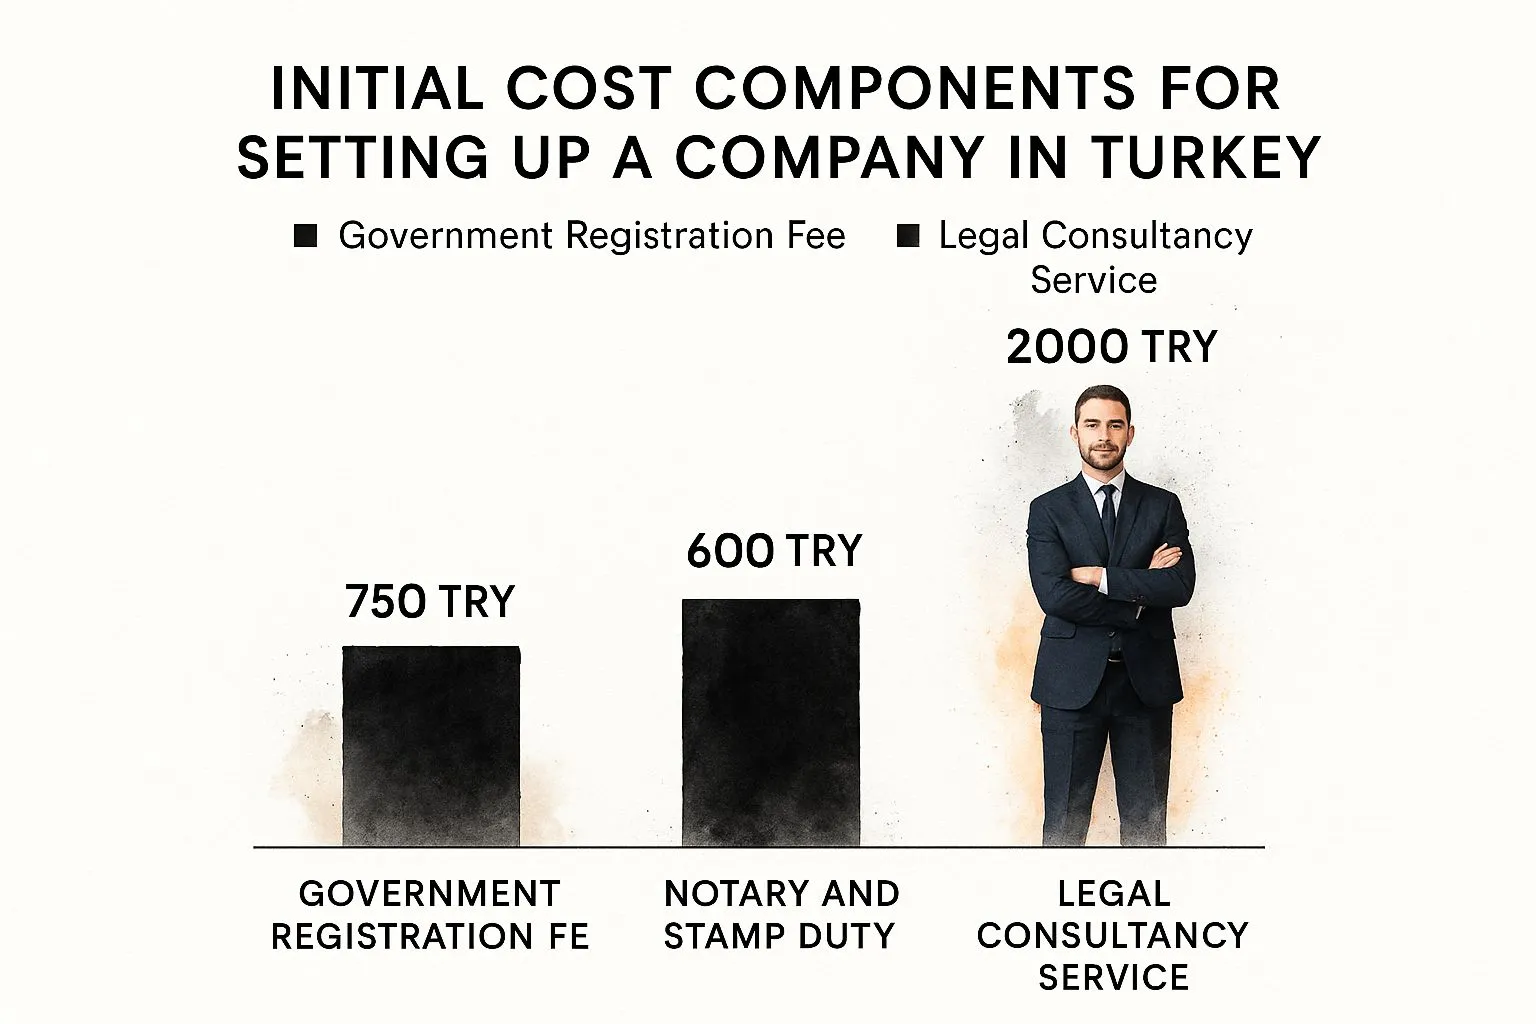
Ask who receives each payment, what it covers and whether it is estimated or fixed for the stated scope.
Share capital is company funding, not a formation fee
At the exchange rate stated above, the minimum capital is approximately EUR 891.50 for a limited liability company (the statutory amount is TRY 50,000) and EUR 4,457.50 for a joint stock company (the statutory amount is TRY 250,000). These TRY thresholds have applied to newly incorporated companies since 1 January 2024, according to the Ministry of Trade announcement.
The payment timing is not the same for both entities. The pre-registration payment of at least 25% of subscribed capital does not apply to limited liability companies; subscribed LLC capital may be paid within 24 months following formation. For a joint stock company, at least 25% of subscribed capital is paid before registration and the remaining amount within two years. The Invest in Türkiye establishment guide explains this distinction.
Capital therefore should not be added to professional and official charges as though it leaves the business permanently. It becomes a company resource, subject to corporate law, accounting treatment and the company’s legitimate needs.
Keep one formula-based official payment separate from that capital line: current Invest in Türkiye guidance states that 0.04% of the company’s capital is paid to the Competition Authority through the Trade Registry process. It is an official formation payment, not additional share capital and not a Workon or licensed-professional fee.
Share capital and formation expenses belong in separate budget lines.
What the 2026 Istanbul CPA tariff adds to the budget
The Istanbul Chamber of Certified Public Accountants (İSMMMO) publishes a workload-based professional fee tariff for 2026. It provides a source-backed reference for work performed under a licensed SMMM/CPA engagement. It is not Workon’s price list, a schedule of public charges or a complete company-formation quotation.
Selected company and filing transactions
Selected 2026 İSMMMO professional-service tariff rows
| Tariff row |
Original TRY amount |
Approximate EUR* |
Budgeting note |
| Limited company establishment |
TRY 9,090 |
EUR 162 |
A professional-service tariff row; not capital or the full formation cost |
| Joint-stock company establishment |
TRY 11,230 |
EUR 200 |
A professional-service tariff row; not capital or the full formation cost |
| Foreign-capital company establishment |
TRY 25,450 |
EUR 454 |
Relevant to foreign-investment files; applicability is determined by the licensed professional |
| Address change |
TRY 4,540 |
EUR 81 |
Transaction-specific professional work; institutional and document costs remain separate |
| Share transfer |
TRY 5,330 |
EUR 95 |
Does not include every legal, notarial, registry or document cost that the case may require |
| Limited company capital increase |
TRY 18,170 |
EUR 324 |
Professional-service row; additional reports or official/document costs may apply |
| Joint-stock company capital increase |
TRY 22,460 |
EUR 400 |
Professional-service row; additional reports or official/document costs may apply |
| Corporate income-tax return |
TRY 6,730 |
EUR 120 |
Whether separately chargeable depends on the engagement and the inclusion rule in the tariff notes |
These are separate or alternative tariff rows, not a shopping list to total automatically. In particular, the limited/JSC establishment row and the foreign-capital establishment row should not be added together unless the licensed professional confirms that the tariff and actual scope require it. The tariff notes also state that certain declaration-signing work is not charged separately in addition to bookkeeping where the specified arrangement applies.
Why a monthly CPA fee cannot be reduced to one number
For balance-sheet bookkeeping, the tariff uses the enterprise’s economic class and digital-ledger file size. The following ranges show the lowest and highest base entries within each scale group before applicable additions and reductions.
2026 İSMMMO balance-sheet bookkeeping base ranges
| Economic scale |
Tariff classes |
Monthly base range in TRY |
Approximate monthly EUR range* |
| Micro |
1–3 |
TRY 7,985–19,165 |
EUR 142–342 |
| Small |
4–6 |
TRY 10,381–23,956 |
EUR 185–427 |
| Medium |
7–9 |
TRY 12,776–28,747 |
EUR 228–513 |
| Large |
10–12 |
TRY 15,172–33,538 |
EUR 271–598 |
The final reference can change because the tariff notes provide additions or reductions for the number of branches, work at the client’s premises, foreign-trade transactions, İstanbul’s population, inflation adjustment, technology-development-zone status, employees and inactive status. The notes calculate each applicable adjustment from the base amount and limit total reductions to 50% of that base.
Illustration, not a quote: if a licensed professional classifies a company in class 1 with a 0–12 MB ledger file, the base is TRY 7,985. Applying the tariff’s İstanbul population addition of 35% and the 25% reduction for a balance-sheet taxpayer with no employees produces TRY 8,783.50, approximately EUR 157 at the stated exchange rate. If the 10% foreign-trade addition also applies, the illustration becomes TRY 9,582, approximately EUR 171. The actual classification, applicable adjustments and engagement scope must be confirmed by the licensed SMMM/CPA.
*Approximate EUR figures use EUR 1 = TRY 56.0853 on 28 August 2026. The tariff’s original denomination is TRY. Its notes state that tariff figures include VAT; actual invoicing and tax treatment must still be confirmed in the professional engagement. Source: İSMMMO Professional Fee Tariffs. These figures are references, not a Workon quotation.
One-time formation costs and first-year operating costs
Registration is one milestone. A company may also need a usable registered address, licensed CPA onboarding, tax-office commencement inspection preparation, a corporate bank-account application, KEP and e-signature, invoicing readiness, employee registrations or sector-specific approvals. Not every business needs every item on the same day, but leaving them outside the budget can make a low formation quote misleading.
| Timing |
Typical categories |
Question to ask |
| Before or during registration |
Document preparation, translation, notarization, official filing payments, agreed coordination scope and any capital due at that stage |
Is this figure fixed for the reviewed documents, or an estimate? |
| Immediately after registration |
Signature and tax steps, licensed CPA engagement, address verification preparation, banking application and operational access tools |
Does the quote end at the registry certificate or continue to operational setup? |
| Ongoing |
Registered address, licensed CPA fees, filings, payroll where applicable, banking, software, employees and sector obligations |
Which costs recur monthly, quarterly or annually? |
Workon coordinates the agreed setup workflow. Services reserved to licensed or regulated professionals are performed under their own professional authority and engagement. This is why a client may pay Workon and a licensed SMMM/CPA separately. See the Turkish CPA requirement guide for the role of the licensed professional.
Translation, notarization and legalization are variable costs
There is no dependable universal per-page or per-document price for an international incorporation file. Language, character count, page count, document type, number of originals or copies, the notarial act, legalization route and exchange rates can all change the result.
For foreign corporate shareholders and branches, documents issued outside Türkiye can require notarisation or another official certification, apostille or Turkish-consular legalisation, and Turkish translation/notarial handling depending on the issuing country, document type and receiving authority. Do not assume every foreign document needs notarisation before apostille or that every country uses the Hague route. Workon’s guides to sworn translation, apostille requirements and powers of attorney explain the separate steps.
A transparent method is to review the documents first, collect an estimated Türkiye-side document budget and reconcile it against the actual cost. If actual-cost billing will be used from the outset, that method should be stated in writing before the work begins.
Three real files show why document costs vary
The following anonymized figures come from completed Workon files. They illustrate document variability only. They are not current quotations and do not represent the total company-formation cost.
| Historical file |
Sworn translation |
Notary |
Combined document cost |
Original TRY total |
| Foreign legal-entity shareholder, July 2026 |
EUR 111.44 |
EUR 252.38 |
EUR 363.82 |
TRY 20,404.78 |
| Foreign legal-entity shareholder, November 2024 |
EUR 151.55 |
EUR 431.55 |
EUR 583.11 |
TRY 32,703.78 |
| Foreign-company branch, March 2025 |
EUR 285.28 |
EUR 880.80 |
EUR 1,166.08 |
TRY 65,400 |
The November 2024 file included approximately 17 translated pages and several corporate documents. The branch file required a substantially heavier document set. Neither should be used to price a simple individual-owned LLC.
Variable document costs are not hidden when the scope and reconciliation method are explained in advance.
Build Your First-Year Company Budget in Five Steps
- Define the legal scenario first. Fix the entity type, shareholder profile, remote/on-site route and whether the shareholder is an individual or foreign company.
- Separate registration from operations. Build one subtotal for formation and another for the first 12 months of running the business.
- Keep capital outside the fee total. Show statutory share capital as company funding, not as money paid to Workon, a professional or the state.
- Mark every variable item. Translation, notarisation, legalisation, courier, banking and activity-specific costs should be labelled fixed, estimated or actual-cost.
- Stress-test the budget against day-one needs. Check whether the company must also budget for a registered address, licensed CPA work, banking, digital tools, employees, work permits or sector licences before the intended activity can begin.
Budgeting rule: A realistic first-year figure is the amount required to move from document preparation to the operating state your specific business actually needs—not merely the amount required to obtain a Trade Registry registration.
How to compare two company-formation quotations
Put both offers into the same scope before comparing the totals. Check the following points:
- Which entity and shareholder scenario does the quote cover?
- Is VAT included, excluded or recoverable subject to the company’s tax position?
- Which payments go to Workon, public institutions and licensed professionals?
- Are translation, notarization, apostille, consular legalization, copies and courier included, estimated or billed at actual cost?
- Are documents and costs arising in the shareholder’s home country included?
- Is share capital shown separately from fees?
- Does the scope end at registration, or include address, CPA onboarding, banking and operational readiness?
- Which items recur after the company is registered?
A proposal that answers these questions is more useful than a lower headline price with undefined exclusions.
There is no reliable universal all-in amount. The total depends on entity type, shareholder profile, foreign-document workload, official and professional costs, registered address, banking and what the business needs after registration. Compare scope-based budgets rather than old USD or TRY headline ranges.
The current general statutory minimum is TRY 50,000 for an LLC and TRY 250,000 for a JSC. Capital is company funding rather than a service fee or government charge.
Treat capital as company funding, not as a provider or government fee. Payment timing depends on the company type, so model the actual cash timing separately from one-time formation charges and recurring operating costs.
Budget the address or workspace according to the real activity and contract term. A virtual or serviced address can suit eligible light-presence businesses, while staff, stock, customer access, equipment or licensing can require additional or dedicated premises.
Yes, depending on the business. Recurring costs can include registered address or workspace, licensed accounting and tax work, banking, digital tools, payroll and employees, work permits and sector-specific compliance. These should be budgeted separately from one-time formation costs.
A foreign corporate shareholder can need additional current-status records, constitutional documents, corporate approvals and signatory evidence. Legalisation, translation, notarisation and courier costs depend on the issuing country and the actual document file, so compare these items separately in the quotation.
Need a scope-based formation plan? Workon provides end-to-end company-registration and operational setup coordination for foreign founders and companies entering Türkiye. Regulated services are carried out by the relevant licensed professionals.
Review Workon’s company-registration coordination in Türkiye
Sources and methodology
This article provides general information and budgeting methodology. It is not legal, tax or accounting advice, and it is not a quotation.

























