





















For an active foreign owner of a business operating under the balance-sheet method, Turkey’s ordinary company-partner rules require three capital and ownership tests at application: the owner’s own capital share must be at least TRY 500,000, the company’s total paid-up capital must be at least TRY 500,000, and the owner must hold at least 20%. The business must then employ at least five Turkish citizens every month from the beginning of permit month seven. These requirements are cumulative at their applicable stage—not alternative routes. The Ministry states that the listed tests do not apply when the foreign partner’s own capital share is at least USD 100,000, but that exception does not guarantee approval.
Last reviewed: 17 September 2026. This eligibility guide reflects the Ministry of Labour and Social Security criteria available on that date, including the general criteria effective from 3 August 2026. Rules, evidence requests and system treatment can change; verify the live official criteria before making an investment or filing.
| Eligibility question | 2026 answer |
|---|---|
| Does share ownership itself create a right to work? | No. Incorporation, a tax number, shares or a residence permit does not authorise active work or management. |
| Do the TRY 500,000 and 20% tests replace one another? | No. Under the ordinary partner criteria, the owner’s own capital-share amount, the company’s total paid-up capital and the ownership percentage must each pass. |
| Must five Turkish citizens already be employed on day one? | The company-partner criterion starts at the beginning of the permit’s seventh month and must then be met every month. |
| What changes at a USD 100,000 capital share? | The Ministry says the listed capital, shareholding and employment criteria do not apply; route, role, document, sector and discretionary evaluation remain. |
| Where is the filing process explained? | Use the separate company-owner work-permit application guide after the eligibility decision is documented. |
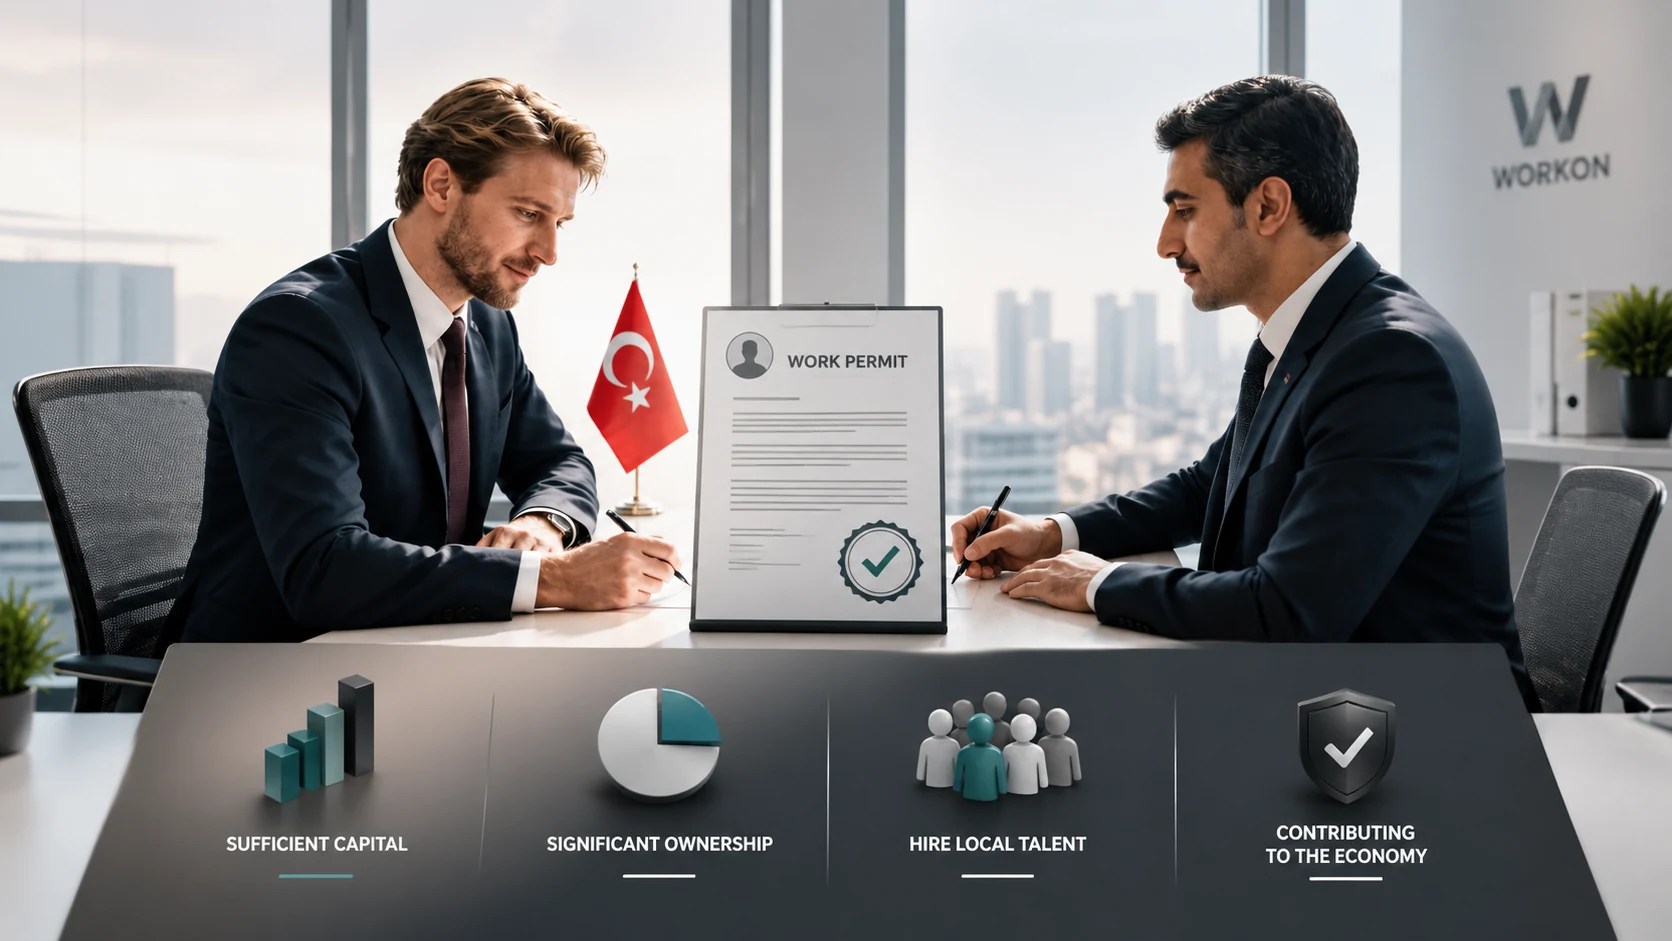
Owner eligibility combines capital, shareholding and time-phased Turkish-employment controls; no single gate replaces the others.
First separate passive ownership from active work
The threshold analysis matters when the foreign shareholder will actively manage, represent or work for the Turkish business. The real conduct matters more than the label placed on the person. Signing contracts, directing staff, carrying out sales, delivering services or running daily operations can point to active work even if corporate documents use a broad investor title.
| Owner position | Initial work-authorisation view | Control |
|---|---|---|
| Passive shareholder receiving investment returns, with no management or productive duties | Ownership alone is not work | Keep authority, workplace presence and actual conduct consistent with the passive role. |
| Non-resident board member of a Turkish joint-stock company | The Ministry identifies this within the work-permit exemption framework | Confirm non-residence and the exact board role before relying on the exemption. |
| Non-managing partner of another Turkish company type | The Ministry identifies this within the exemption framework | Confirm that the person does not manage the company or provide services in Turkey. |
| Managing partner, active director or shareholder working in the business | Work authorisation is generally required | Run the company-partner tests and obtain the required authorisation before productive work begins. |
An exemption should not be assumed from the company type alone. If the planned duties, signature authority or residence pattern do not fit the limited passive category, define the operating role before the owner acts. A business visit, residence permit or company signature circular is not a substitute for work authorisation.
Apply the time-phased company-partner tests together
The Ministry’s company-partner criteria apply to businesses operating under the balance-sheet method. Unless the USD 100,000 capital-share exception applies, test the same applicant and company against three concurrent application gates and one continuing condition.
- Owner’s own capital share: at least TRY 500,000. This is the registered capital amount attributable to the foreign partner—not the company’s headline valuation, projected investment, loan balance or planned future contribution.
- Total paid-up capital: at least TRY 500,000. The company itself must meet this floor. An authorised but unpaid capital commitment should not be treated as paid-up capital without source evidence supporting that status.
- Foreign owner’s shareholding: at least 20%. Passing the TRY amount does not cure a percentage below 20%, and a percentage above 20% does not cure an owner capital share below TRY 500,000.
- Five Turkish employees from permit month seven. The business must employ at least five Turkish citizens every month beginning with the seventh month of the permit. This is a continuing monthly condition, not a one-time headcount snapshot.
The capital amount and percentage must describe the same owner’s effective share at the same point in time. Reconcile the trade-registry record, company books, paid-up-capital evidence, financial statements and e-İzin data. If a share transfer or capital increase is still pending, do not calculate eligibility as though it were complete.
Use worked examples to avoid the common calculation error
| Scenario | Calculation | Threshold result |
|---|---|---|
| A: Total paid-up capital TRY 2,000,000; foreign owner holds 30% | Owner’s capital share = TRY 600,000 | The capital and ownership gates pass. The business must still meet the five-Turkish-citizen condition from permit month seven and the file remains subject to other review. |
| B: Total paid-up capital TRY 1,000,000; foreign owner holds 25% | Owner’s capital share = TRY 250,000 | Fails the ordinary owner-share amount even though total capital and 20% ownership pass. A future, legally completed capital change may alter the result; a plan does not. |
| C: Total paid-up capital TRY 6,000,000; foreign owner holds 10% | Owner’s capital share = TRY 600,000 | Fails the 20% gate even though both TRY 500,000 capital figures pass. |
| D: Foreign partner’s documented capital share is at least USD 100,000 | Test the actual capital share against the Ministry’s USD condition | The Ministry says the listed capital, percentage and five-employee criteria do not apply. Approval is not automatic; prove the basis and continue the remaining eligibility review. |
These examples isolate the threshold logic. They do not predict a Ministry decision. Company type, sector, the reality of the role, document consistency, restricted professions, prior authorisation and other statutory considerations can still affect the application.
Treat the USD 100,000 rule as an exception, not an approval route
The Ministry’s published criterion states that the listed company-partner criteria do not apply where the foreign partner’s capital share is at least USD 100,000. The relevant value is the foreign partner’s own capital share, not company revenue, exports, an asset purchase, a shareholder loan or the company’s entire value.
Before relying on the exception, document the capital contribution, the ownership record and the currency-conversion basis accepted for the case. Keep the same figures and effective date across the registry, accounting evidence and application. The exception removes the specified partner thresholds; it does not convert passive ownership into work authorisation, waive the application route, permit work before approval, override regulated-sector controls or bind the Ministry to approve.
Do not mix partner criteria with general workplace criteria
The Ministry publishes general workplace criteria separately from the company-partner rules. For ordinary foreign-employee cases, the general framework includes financial, Turkish-employment and salary tests, with sector- and status-specific variations. A company owner should not substitute a general employee criterion for the dedicated partner test—or assume that satisfying the partner test resolves every other issue.
A general domestic-application relief took effect on 3 August 2026. It concerns a foreign national who has legally resided in Turkey for at least one year during the previous three years under a work permit, residence permit or international-protection status. For up to three qualifying foreign employees at a workplace, the Ministry states that the general employment and financial criteria are not applied, provided the number covered by the relief does not exceed the number of Turkish citizens employed there.
That relief sits in the general criteria; the company-partner requirements are stated in their own section. Apply the partner’s TRY 500,000, 20% and month-seven staffing tests according to the Ministry’s live rules and the specific owner case. Salary and sector-specific controls also remain separate. For ordinary employee criteria, use the separate Turkey work-permit guide.
Build an eligibility evidence matrix before filing
Evidence depends on the company type, financial period, route, sector and Ministry requests. Use the table as a control framework rather than a universal document list.
| Eligibility issue | Typical source evidence | Decision control |
|---|---|---|
| Active or passive role | Articles, shareholder and board resolutions, registry appointments, representation authority and a factual duty description | Corporate titles, signature power and real activity must point to the same classification. |
| Company identity and legal status | MERSİS, trade-registry and tax records; current Trade Registry Gazette entries | Use the same legal name, registration number, company type and address in every source. |
| Total paid-up capital | Current registry records, company books and financial evidence appropriate to the company | Separate authorised or committed capital from the amount actually paid and recorded. |
| Owner’s capital share and percentage | Share ledger or partnership records, acquisition or capital-increase documents and matching accounting evidence | Calculate the TRY amount and percentage for the same owner on the same effective date. |
| USD 100,000 exception | Capital contribution and ownership evidence plus a traceable valuation/conversion basis | Do not substitute loans, turnover, exports, asset values or future investment. |
| Month-seven Turkish employment | SGK workplace and monthly employee records | Monitor at least five Turkish citizens every applicable month, including staff changes and reporting cut-offs. |
| Sector and role permission | Activity certificate, licence, prior authorisation or professional record only where required | Check restricted professions and regulator conditions independently from the capital calculation. |
Do not obtain notarisation, apostilles, diploma equivalency, health records, no-debt letters or business plans by habit. Map each requested item to the live Ministry screen, the issuing jurisdiction and the actual regulated activity. Workon’s guides to company formation in Turkey, MERSİS company registration and the activity certificate explain upstream corporate records that may support this matrix.
Build the evidence set from the owner’s actual role, current registry records and the live case-specific document request.
Plan the five-employee condition before month seven
A business that passes the capital tests but cannot sustain the staffing condition has not completed the eligibility analysis. Build a month-by-month forecast from the permit start date, not the application date. Identify when month seven begins, which employees are Turkish citizens, whether their SGK registration belongs to the correct workplace and how departures or unpaid gaps could affect the recorded count.
Do not hire nominal employees only to manufacture a threshold. Roles, payroll, attendance, SGK declarations and business activity should reflect genuine employment. Coordinate the control with SGK employer registration and payroll setup in Turkey. Where the USD 100,000 exception is used, retain the supporting capital evidence through the permit period because the Ministry may review the basis of the application.
Recheck eligibility at renewal and after corporate changes
Approval is not a permanent finding that every future arrangement qualifies. Monitor the permit annotation, company status, owner percentage, paid-up capital, Turkish headcount and actual role. A capital reduction, new share issue, transfer, merger, workplace move, SGK registration change, change of management authority or shift from passive to active duties can change the analysis or require a new filing.
Before renewal, reconcile the complete permit-period record rather than taking a filing-date snapshot. Keep monthly staffing evidence for the period in which the five-citizen requirement applied. If the case relied on the USD 100,000 exception, verify that the owner’s documented capital position and the Ministry’s live criterion still support it. The separate company-owner application guide explains domestic and overseas routes, e-İzin filing, fees, post-approval controls and extension timing.
Recheck ownership, capital, staffing and the real management role after corporate changes and before renewal.
Use a clear go, fix or stop decision
| Decision | When to use it | Next action |
|---|---|---|
| Go to application preparation | The role requires authorisation; all four ordinary partner tests pass, or the USD 100,000 exception is fully supported; sector and company records are consistent. | Freeze the evidence set and move to the application workflow without allowing work to start early. |
| Fix before filing | A real, lawful capital, registry, authority or evidence issue can be completed and documented. | Finish the corporate action first, then recalculate from the effective records. Do not file on planned facts. |
| Stop and reassess | The owner will work but neither the ordinary thresholds nor a documented exception applies, the role is restricted, or the claimed passive position conflicts with actual duties. | Change the genuine operating structure, obtain case-specific advice or delay the activity; do not disguise the role. |
Official sources checked for this eligibility guide
- Directorate General of International Labour Force — current work-permit evaluation criteria
- Ministry of Labour and Social Security — work-permit FAQ
- Directorate General — conditions for foreigners opening a company or workplace
For a coordinated eligibility and filing review, see Workon’s residency and work-permit support. Base the decision on the owner’s real duties, effective corporate records and the official criteria in force when the application is made.
Frequently Asked Questions
Note: Last reviewed September 2026. This guide provides general operational information on company-owner work-permit eligibility. Case-specific immigration, corporate, tax, employment and social-security work is coordinated with the appropriately qualified professionals under the Ministry rules effective for the application.




